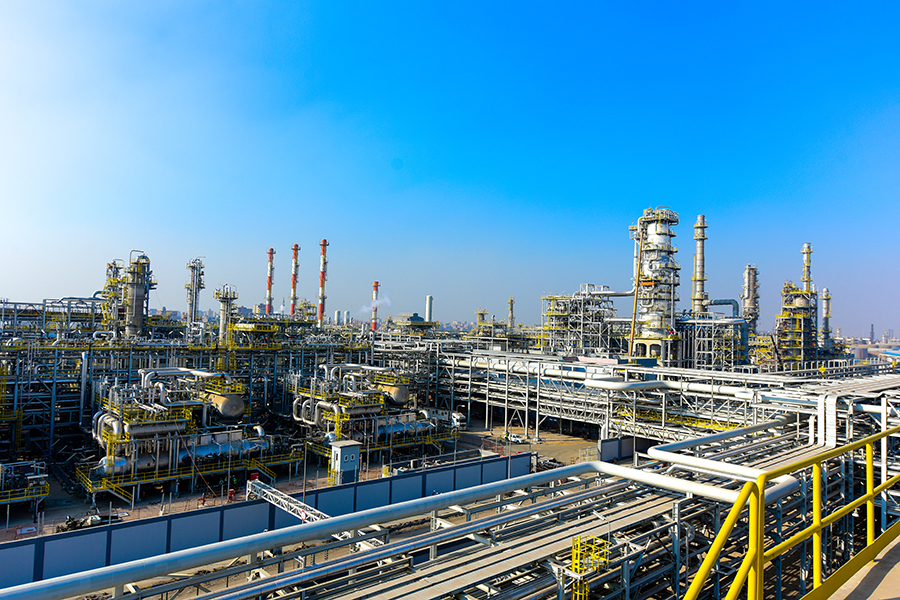
The Huawei-backed battery plan covers under a third of Egypt’s needs

1

WHAT WE’RE TRACKING TODAY

A Saudi-Egyptian consortium plans a SAR 1 bn real estate fund

Good morning, everyone. We’ve got two reads for you today about how Egyptian companies are putting fresh capital to work — one at the scale of the national grid and another at the scale of a single factory floor.

But first, we have a follow-up on the US Treasury Department’s proposed sanctions on the UAE outpost of Banque Misr. The Central Bank of the UAE and the Central Bank of Egypt issued a joint statement affirming “full and continuous cooperation and coordination between them with regard to the branches of Banque Misr in the UAE conducting all their business as usual,” adding that the branches will take all necessary actions and measures within the period specified for that purpose. The UAE branch has thirty days from the warning was issued on Friday to provide comment, so we’re keeping an eye out for how they respond.

Back to batteries, the Huawei story is the bigger read. The Electricity Ministry is advancing plans to build 4 GWh of battery storage, financed in EGP, with Huawei Egypt as the partner. The plan covers under a third of Egypt’s 14.3 GWh of storage it wants to build by 2028, as outlined in its renewable roadmap, and with renewable capacity set to triple in the same period, the math is crunching fast.

On the factory floor, Future Care for Medical Industries, which was just promoted to the main market, is building a medical-sterilization products factory for up to EGP 100 mn, targeting Gulf and Africa export sales. Half the bill comes from the same capital increase it raised to make it to the main board in the first place. The other half of the financing is still to come.

***

ARE YOU MORE OF A LISTENER? Morning Drive is a 10-minute summary of today’s issue crafted for you to enjoy with your morning coffee, while getting the kids ready for school, or driving through the morning rush. And if you like it, tell your friends to tell their friends. They can find us on Apple, Spotify, or wherever they get their podcasts.

***


The Chinese takeover with Ankush Arora: When Chinese cars first appeared in Egypt around a decade ago, they were met with backlash. Now, they’re everywhere. Why? And how?

On this episode of Making It, Ankush Arora, CEO of Al Mansour Automotive Group, joins Patrick to break down how this happened, and why the pace of adoption is accelerating.

Listen to the episode on: Apple Podcasts | Spotify | Anghami | YouTube

Sign up to our newsletter to get Making It in your inbox.


Our REIF pipeline just got a Saudi entrant

A Saudi-Egyptian consortium is setting up a real estate investment fund (REIF), branded Asl, spanning Egypt and KSA — and plans to deploy up to SAR 1 bn (c. USD 266.7 mn) here in its first year, through Asl Holding, with a focus on real estate and hospitality, Chairman Haitham El Sherbiny told Al Arabiya. The plan lands a week after Asl Holding acquired local developer Zurich Developments and Saudi contractor Alkayan, which between them carry a stated investment value of roughly EGP 50 bn. Neither transaction’s price has been disclosed.

What’s still being set up: Asl Holding is in the final stages of securing Financial Regulatory Authority (FRA) approval to become a holding company in Egypt — a vehicle to develop and manage the acquired companies’ projects, CEO Ahmed Attia said. That approval is separate from the fund itself, which would need its own FRA license before it can raise money.

IN CONTEXT- Six licensed REIFs held combined net assets of roughly EGP 12.6 bn at the end of 2Q 2026, up from EGP 9 bn a quarter earlier, with the FRA reviewing more than 20 new applications on top of the 23 already pending, an FRA official told EnterpriseAM earlier this month.

The plan: Asl Holding is targeting 1k new hotel keys over three years and weighing a move into the Red Sea, bringing in international operators to run the rooms. Its portfolio spans seven projects across New Damietta, New Mansoura, Sheikh Zayed, and New Cairo, where it holds a 35-feddan plot. A Fifth Settlement launch is due in October and a second Sheikh Zayed project before year-end.

BACKGROUND- The state is counting on private money for almost all of its tourism buildout, with hotel acquisitions and partnerships expected to do much of the heavy lifting on new capacity. Of the EGP 118.5 bn in tourism and antiquities investment planned for FY 2026/27, private investors are expected to put up EGP 117.8 bn — 99% of it — according to a government document seen by EnterpriseAM. The market added some 6k rooms in 1H 2026 alone.

Another pin on Taqa’s regional map

EGX-listed Taqa Arabia is making its first move into Jordan, with a 14-km natural gas pipeline for Al Rawdah Industrial City in the Ma’an Development Area, according to an EGX disclosure (pdf). The company signed the contract with Jordan’s Energy and Mineral Resources Ministry to supply and build the line, and its board approved setting up a Jordanian branch earlier this month to run the operation.

The pipeline is one leg of a bigger, Abu Dhabi-funded package. It falls under a USD 70 mn program backed by the Abu Dhabi Fund for Development to connect two Jordanian industrial cities — Al Rawdah and Al Muwaqqar — to natural gas, according to a statement from Jordan’s energy ministry. Taqa Arabia holds only the Al Rawdah leg, while the sister Al Muwaqqar project went to a consortium of Petrojet and Jordan’s Ahmad Yousef Al Tarawneh, under a USD 22.7 mn contract announced by the oil ministry on Thursday. Neither Taqa Arabia nor Amman has said how much of the USD 70 mn is Taqa’s, and the company did not offer more information when we reached out.

IN CONTEXT- Jordan is the latest leg of Taqa’s regional gas push. Just last week, subsidiary Rosetta Energy Solutions signed a binding agreement, targeting commercial operations in 2027. Outside Egypt, Taqa Arabia says it currently operates in Saudi Arabia, Qatar, Tanzania, Mozambique, and Pakistan.


PSA-

WEATHER- It’s a tad easier to bear in Cairo today, with a high of 34°C and a low of 24°C, according to our favorite weather app.

It’s a bit cooler in Alexandria, with a high of 32°C and a low of 23°C.

The big story abroad

In the first US strike on Iran in over a month, US forces targeted two Iranian rocket launchers on Larak Island in the Strait of Hormuz. US officials called the action a preemptive strike, reporting that Iranian forces were preparing to deploy sea mines into the waterway. Iran responded by launching missiles toward Jordan, though they were reportedly intercepted.

In the M&A scene: Ins. broker and consulting firm Aon is closing in on an agreement to acquire KKR-owned ins. broker USI for around USD 17 bn, expanding Aon's ability to serve midsize businesses. The move — the latest in a spate of big exits for KKR — is projected to be accretive to earnings per share starting in 2028.

Shein’s value shrinks pre-IPO: China’s fast fashion giant Shein is on track to go public tomorrow at a valuation amounting roughly one quarter of its 2022 value of USD 100 bn. The decline coincides with ebbing investor enthusiasm for Chinese consumer IPOs, as high-profile AI debuts stole the market's attention over the past year.

*** It’s Blackboard day: We have our weekly look at the business of education in Egypt, from pre-K through the highest reaches of higher ed.

In today’s issue: We look into how a one-point jump in Egypt’s medical school cutoff slashes acceptances by 10%.

A strategic partnership shaping the next chapter of the Red Sea

Somabay and MARAKEZ come together in a landmark partnership, marking MARAKEZ’s first entry into Egypt’s Red Sea market and a significant step forward in the continued evolution of Somabay.

2

Energy

Egypt’s Huawei-backed battery plan will be financed in pounds — and covers barely a third of what the grid needs

Electricity Minister Mahmoud Esmat is advancing plans to locally manufacture battery energy storage systems and build standalone storage stations totaling 4 GWh, financed in EGP, after meeting Huawei Egypt CEO Benjamin Hou, according to a statement. The two reviewed technical and economic feasibility studies for proposed storage sites on the national grid, along with the terms and obligations needed to start the manufacturing plant. Talks also covered digital transformation, smart-grid solutions, data centers, and upgrades to grid communications, part of the shift from a traditional to a smart grid.

REMEMBER- Chinese President Xi Jinping is visiting Egypt this week — his first visit in a decade — and Huawei’s AI push is one of the threads to watch. The Chinese tech giant wants to build data centers in Egypt stocked with two classes of advanced AI chips, one for AI training clouds, the other for inference. The bid caught Washington’s attention: officials are reportedly preparing a counter-offer for Cairo to weigh. We’ll be keeping an eye out for whether Huawei inks something while Xi’s in town.

The plan points to a project we flagged in May: 4 GWh of battery storage across South Cairo, Damanhour, and Wadi El Natroun, financed through the Tahya Misr Fund and bundled at the time with a separate 4.8 GW of wind capacity. The developer has gone unnamed until now. Mahmoud Abouelnaga — industrial decarbonization expert at UNIDO and nonresident senior fellow at the Atlantic Council — can’t confirm the link, but says the sequence of announcements makes it plausible. More telling, he argues, is what the EGP-financing choice implies regardless of who the developer turns out to be: “the government as the main off-taker is looking into ways to increase their solvency.”

The Huawei plan lands in a crowded field. We tracked Sungrow’s USD 120 mn, 2 GWh plant breaking ground last October, Kemet’s USD 200 mn, 5 GWh tie-up with China’s Cornex in January, and AMEA Power’s EPC contracts for a 3 GWh factory and 1.5 GWh of storage in June. With storage flagged as the missing piece in the push to a 45% renewables share by 2028, the Huawei plan joins a lengthening list of local-manufacturing commitments still working through feasibility studies and licensing.

But 4 GWh may not keep pace. The new capacity is a step in the right direction, Abouelnaga tells us, but won’t be enough to hold curtailment down given Egypt’s target to nearly triple renewable capacity — from 9.5 GW today to 27.7 GW by 2028. The government’s own renewable expansion roadmap calls for 14.3 GWh of storage by that same year, meaning the Huawei plan covers under a third of what the roadmap says the grid will actually need. “If storage capacity stalled while renewable capacity tripled, curtailment would probably skyrocket,” Abouelnaga says.

“Local manufacturing” here means assembly, not cell production. Abouelnaga draws the line between battery-system assembly and integration on one side and the chemical manufacturing of cells on the other — and Egypt’s strategy is built around the former. With no commercial mining of lithium, cobalt, or nickel, he expects the country’s role to stay concentrated in pack assembly, software integration, and structural housing, with cells imported.

Who pays for all this is worth flagging. Egypt’s BESS pipeline is largely debt-financed by DFIs and multilateral lenders — IFC, EIB, EBRD — whose money typically comes tied to subsidy phase-out, Abouelnaga notes. In a developing economy, the cost of that phase-out tends to land on ordinary consumers — a dynamic worth watching as Egypt’s recent tariff hikes keep biting.

The EGP-financing detail raises an FX question. Huawei’s hardware runs on USD-denominated LFP cell imports, while the ministry says the financing is in EGP. Abouelnaga sees three ways a foreign provider manages that gap: push the risk onto a local partner — AIS, here — rather than carry it directly; keep the high-margin proprietary kit (power conversion systems, cooling networks) while offloading bulkier, lower-value assembly to cut USD exposure per MWh; or lean on Cabinet Decree 54/2023 — whose renewable land-use regime was extended to storage — letting developers pay a land fee of at least 2% of annual output instead of buying land outright.

Where the 4 GWh lands will shape its payoff. Co-locating with generation hubs like Benban or the Red Sea would capture cheap electrons at source, help the government dodge penalties under the “take-or-pay” clauses in its long-term PPAs with private developers, and ease transmission bottlenecks by feeding stored solar into the grid gradually rather than all at once. Siting near industrial centers instead shifts the benefit to peak shaving, cutting costs for industrial users while firming up voltage. Abouelnaga sees merit in both.

What to watch: The feasibility studies and licensing terms the ministry says will gate the plant’s start, and the siting call that decides whether the 4 GWh shaves industrial peaks or firms up solar at Benban. Neither the developer nor a timeline is public yet, both are the next disclosures to watch for.

(** Tap or click the headline above to read this story with all of the links to our background as well as external sources.)

This publication is proudly sponsored by

3

Investment Watch

Newly promoted Future Care earmarks its capital raise for an EGP 100 mn export factory

Newly main market-promoted Future Care for Medical Industries will build a medical-sterilization products factory for up to EGP 100 mn to lift capacity and expand into export sales to the Gulf and Africa, the company told the EGX in a filing (pdf). Half the cost will come from the capital increase it carried out to reach the main board; the rest from financing sources it hasn’t yet named.

The raise was earmarked for this all along. Future Care flagged the factory in a feasibility study and forward plan it filed as part of its promotion, the company said. That means the capital increase that got it onto the main board was never only about clearing the threshold. The increase came to EGP 57.5 mn (to EGP 115.2 mn, from EGP 57.7 mn), and the company says up to half the factory’s bill — as much as EGP 50 mn — will lean on it. Most of the fresh capital, in other words, is already spoken for.

REMEMBER- Future Care — formerly International Company for Medical Industries — began trading on the main board last week, graduating from the SME market after 14 years. The move required nearly doubling its capital to EGP 115.2 mn from EGP 57.7 mn to clear the EGP 100 mn minimum for a main-market listing, opening the stock to index and institutional mandates that don’t reach the SME board. It was the year’s second SME-to-main transfer, after non-bank lender Tawasoa for Factoring made the move in June.

What’s still open: Only phase one draws on the capital increase; anything beyond that goes back to the board and general assembly to weigh other financing, the company said. It named no site, no timeline, and no source for the other half of the bill.

(** Tap or click the headline above to read this story with all of the links to our background as well as external sources.)

4

A MESSAGE FROM VISA

AI agents are entering the checkout flow. Visa is getting the payment layer ready

Tokenized transactions in Visa’s Central and Eastern Europe, Middle East, and Africa (CEMEA) region jumped from 26% in 2023 to 70% in 2026, while regional stablecoin settlement volumes rose nearly 60x in one year. Globally, Visa is moving stablecoins across VisaNet at an annualized rate of USD 7 bn, with more than 160 card programs live or in development. Ahead of the Visa Payments Forum in Paris, the company laid out the infrastructure work behind those numbers — and the next phase of digital commerce now coming into view.

Start with identity. As AI agents begin to shop, compare, and check out on consumers’ behalf, Visa's new Agentic Directory verifies which agents and merchants are legitimate participants in agentic commerce. Agent Score gives merchants a read on whether their websites are ready for automated buyers before those buyers show up at checkout.

Next: tokens with more context. Tokens already mask card numbers. Visa is now adding richer transaction context and a token assurance signal based on each token's provisioning and behavioral history, giving banks and merchants more context to assess automated, embedded, and newly initiated transactions.

At the back end, money movement is getting a longer workday. Visa is extending seven-day onchain settlement beyond issuing banks to acquirers, and building Tokenized Deposits, a technology layer that allows banks to turn traditional deposits into programmable digital money while keeping funds on the balance sheet.

For banks and merchants in Egypt and the wider CEMEA region, the takeaway is readiness. AI agents are entering the purchase journey. Tokens are carrying more trust data. Stablecoins are moving value more frequently. The payment layer beneath digital commerce is being rebuilt to enable faster transactions that run more automatically and securely than ever.

5

Also on our Radar

Sodic secured an EGP 7.5 bn CIB facility to finance its June North Coast project

Our friends at Sodic have secured an EGP 7.5 bn medium-term facility from CIB to finance development and construction of its June project in Ras El Hekma, according to a statement seen by EnterpriseAM. The 280-feddan North Coast development includes villas, serviced apartments, and a Marriott Tribute Portfolio hotel.

CIB has financed June before: Sodic subsidiary Tabrouk for Development secured an EGP 2.5 bn bridge loan from the bank for the project in March 2025. The latest facility is three times the size of that earlier financing, though Sodic did not say whether the new loan replaces, refinances, or sits alongside the bridge facility.

June also forms part of Sodic’s wider North Coast hospitality push. The developer said last year that the planned 180-room Tribute Portfolio hotel at June would be part of an EGP 10 bn-plus hospitality expansion through 2029.

Governance is the curriculum

The state’s IPO pipeline just graduated its first class: Some 118 executives from 34 state-owned companies completed the first round of the Financial Regulatory Authority’s (FRA) IPO-readiness training program, with every participant passing the end-of-course exam, the regulator said in a statement. The program launched in late July as the first national initiative built specifically around the state’s privatization program.

The participants: The cohort drew from companies already temporarily listed on the EGX, others earmarked for listing in the next phase, and the State Ownership Unit. It worked through what it takes to move from temporary listing to final listing to an actual float: governance, disclosure, and the continuing obligations that kick in once a company is on the board.

Container upgrade

The Transport Ministry plans to invest c. USD 160 mn to build four new container ships in China, with manufacturing set to start in 2028 and take about four years, Asharq Business reports, citing three government officials. A final agreement is expected by the end of 2027, and the ships would be self-financed through the Holding Company for Maritime and Land Transport and its subsidiary National Navigation Company (NNC). Transport Minister Kamel El Wazir is conditioning the agreement on Chinese participation in a new ship-repair yard in Alexandria — backed by three Egyptian entities — as part of a push to localize repair and maintenance work and cut reliance on foreign yards.

REMEMBER- NNC received two dry bulk carriers from China’s New Hantong Shipyard earlier this month, bringing its fleet to 16 vessels, a step toward the ministry’s target of 40 state-owned vessels by 2030. Egypt’s wider merchant fleet stands at 142 vessels, but only 84 of them are active, with most tied up in towage, pilotage, and oil-sector work rather than international cargo transport.

IFC puts a number on Shadwan

Scatec’s 900 MW Shadwan wind farm in Ras Shukeir now carries an estimated price tag of up to USD 700 mn, according to an IFC project disclosure — a notable drop from the USD 1 bn figure cited when the company signed a 25-year power purchase agreement (PPA) with the Egyptian Electricity Transmission Company (EETC) last year. IFC is proposing its own USD 100 mn loan plus interest rate and cross-currency swap, with the remaining USD 560 mn coming from parallel lenders, including the EBRD’s proposed USD 192 mn senior commitment. IFC’s board is due to vote on the loan by 30 October. The PPA itself is fully guaranteed by Egypt’s Finance Ministry.

About Shadwan: The site sits on a 90 sq km plot within a wider 350 sq km area allocated to the New and Renewable Energy Authority, according to an IFC disclosure (pdf). It will house 83 wind turbine generators, connected to the grid via a 45-km, 500 kV transmission line to be built by EETC. Early work began in June 2026, with the first 242 MW planned to come online by November 2027 and the full 900 MW by April 2028.

Other news on our radar

  • USD 823 mn — that’s how much the World Bank’s Multilateral Investment Guarantee Agency has grown its portfolio in Egypt between 2015 and 2025. The energy sector took the lion’s share of USD 480 mn, with USD 320 mn earmarked for the 16 Benban solar complex projects. (Al Borsa)

(** Tap or click the headline above to read this story with all of the links to our background as well as external sources.)

6

PLANET FINANCE

Warsh breaks with Powell-era practice at Jackson Hole

Federal Reserve Chair Kevin Warsh used his first Jackson Hole keynote Friday to break with the last 20 years of central bank communication practice — and to signal that the September rate decision is materially harder for our region than the market had priced heading into the weekend. September rate hike odds jumped from around 35% pre-speech to 57% by close, with the two year Treasury yield jumping 6 basis points to 4.298%, the 10-year climbing to 4.72%, and the 30-year sitting at 5.21%.

The substantive argument was hawkish. Warsh recommitted to the Fed’s 2% PCE inflation target and told the audience that despite better-than-expected summer readings, “underlying trends have not meaningfully improved” on inflation. PCE is at 3.7%. Reuters called the remarks the closest Warsh has come to acknowledging additional rate increases could be necessary. Navy Federal’s Heather Long summarized the reaction: “A hike probably won’t come in September, but it will by October or December.”

The framework signal matters more than the September call. Warsh explicitly refused to provide forward guidance, telling markets “we should not indulge a regime in which market participants are looking primarily to the Fed for their next trade.” That is a direct break from Powell-era communication practice, and it reinforced what analysts have been calling Warsh’s biggest change at the Fed: dialing back on communication to markets and the public about the Fed’s future plans. For markets used to reading Fedspeak as the primary input into every asset-pricing decision, this is a structural change in how information flows.

The Washington Post’s take was blunter — Warsh “renewed his inflation-fighting credentials” and put more pressure on the central bank to raise rates when it next meets September 15-16 if inflation doesn’t improve. The July FOMC vote was already 9-3 to hold, with Hammack, Kashkari, and Logan dissenting for a hike. Warsh’s speech gave weight to that dissenting bloc, and put him more clearly at odds with Trump’s demand for lower rates, turning the September meeting into a public test of Fed independence under political pressure.

The regional implications: At least five GCC central banks will follow Warsh wherever he goes, whether they have a domestic case for it or not. The SAR, AED, QAR, BHD, and OMR are all pegged to the USD which means all five central banks have to move within days of the Fed to protect the peg and close off arbitrage. Meanwhile, Kuwait, pegged to an undisclosed basket in which the USD dominates, has some discretion. The catch is that a hike would land on economies running inflation at 1.8% in Saudi Arabia (as of July) and between 2.2% and 3.1% across Kuwait, Qatar, Bahrain and Oman on the most recent prints. The region would then be importing a solution to a problem it doesn’t have which may leave GCC borrowers refinancing at higher rates without a domestic slowdown to justify them.

There’s also more weight to be given to what Warsh did not say. He did not commit to a reaction function. He did not tell markets when the Fed would move. He did not soften his tone in response to political pressure. What he did was recommit the central bank to its inflation mandate while explicitly disclaiming the market’s expectation that the Fed would guide them through every decision. That is a different Fed — and the operating manual for a different Fed does not yet exist for the strategists, treasurers, and CIOs across our coverage area who spent the last 15 years learning the Powell manual.

Bottom line. Friday was the moment the Warsh framework became visible. The September 15-16 meeting is now the calibration event, but the framework governs the next four years regardless of what happens at that meeting. Every long-dated regional issuance decision, every eurobond calculation, every Gulf SWF duration book, and every EM refinancing plan needs to be repositioned against a Fed that has explicitly said it will no longer be the primary input into markets’ next trade.

(** Tap or click the headline above to read this story with all of the links to our background as well as external sources.)

MARKETS THIS MORNING-

Asian share markets dropped earlier today following renewed military conflict between the US and Iran. Escalating geopolitical tensions, alongside rising bond yields, dragged South Korea’s Kospi down 1.8% and Japan's Nikkei down 1.7% while the MSCI Asia-Pacific index — excluding Japan — declined by 0.7%.

EGX30

54,937

-0.3% (YTD: +31.3%)

USD (CBE)

Buy 50.46

Sell 50.60

USD (CIB)

Buy 50.40

Sell 50.50

Interest rates (CBE)

19.00% deposit

20.00% lending

Tadawul

11,159

-0.7% (YTD: +6.4%)

ADX

10,045

+0.1% (YTD: +0.5%)

DFM

5,883

+0.3% (YTD: -2.7%)

S&P 500

7,712

-0.3% (YTD: +12.7%)

FTSE 100

10,824

+0.3% (YTD: +9.0%)

Euro Stoxx 50

6,231

-0.8% (YTD: +11.9%)

Brent crude

USD 89.44

+1.4%

Natural gas (Nymex)

USD 2.85

-1.5%

Gold

USD 4,507

-0.5%

BTC

USD 78,500

+0.4% (YTD: -10.4%)

S&P Egypt Sovereign Bond Index

1,108

+0.1% (YTD: +11.6%)

S&P MENA Bond & Sukuk

151.34

-0.1% (YTD: -0.4%)

VIX (Volatility Index)

14.43

-0.6% (YTD: -3.4%)

THE CLOSING BELL-

The EGX30 fell 0.3% at yesterday’s close on turnover of EGP 12.2 bn (10.3% above the 90-day average). Regional investors were sole net sellers. The index is up 31.3% YTD.

In the green: Orascom Investment Holding (+5.5%), AMOC (+4.9%), and Abu Qir Fertilizers (+4.8%).

In the red: Edita (-3.7%), E-finance (-2.7%), and Raya Holding (-2.4%).

7

BLACKBOARD

A one-point jump in Egypt’s medical school cutoff just cut acceptances by 10%

Getting into medical college in Egypt just got harder. The minimum admission score for human medicine at public universities hit 94.06%, up from 93.12%, Higher Education Minister Abdel Aziz Konsowa officially announced. Other fields were raised, too — dentistry, 93.28%; physical therapy, 92.34%; and pharmacy, 92.03%.

The mechanism behind the squeeze: A government official tells EnterpriseAM that raising the minimum admission score by just 1% cuts the number of accepted students by 10%. According to the official, this year’s hike was set specifically to satisfy the Doctors’ Syndicate’s demands and the recommendation of the government committee formed to study overcrowding in these programs and labor market saturation. The threshold spike is the seat cut itself, already in motion this cycle, rather than a side effect of rising competition.

REMEMBER- Egypt’s admission score thresholds have been climbing steadily, part of a broader pattern of the state scrambling to align higher-ed output with labor-market limits. We flagged a version of this mismatch last month, when the Higher Education Ministry launched a census to count how many postgraduates it’s producing and whether they’re employed. This year’s cutoff jump is the same problem showing up at the admissions gate instead of the graduation stage.

Private universities are raising the threshold too: “Reducing admissions to medical colleges is driven by several factors, including the rising number of graduates, the need to preserve the quality of education and training, and the ability of the domestic labor market to absorb these graduates,” Badr University President Mostafa Kamal tells EnterpriseAM.

The goal, he says, is to provide better educational services and produce a number of graduates in line with labor-market needs, while maintaining Egypt’s ability to supply medical professionals who can work abroad and generate foreign currency. Reaching a real balance could take around five years, Kamal tells us, given the healthcare sector’s capacity and the pipeline of new hospitals that will need medical graduates. Government assignments are now tied to actual staffing needs by health authorities and governorates rather than blanket placement, he adds — a departure from the previous system.

Egypt built its own doctor surplus: The official tells us that recent years have seen disguised unemployment — when more people are employed in a sector than are really needed — among medical graduates, as the government delayed doctor appointments for three consecutive cohorts amid budget cuts. The delay pushed some graduates abroad or into unrelated fields, meaning the state lost part of the return on its investment in training them. “Egypt used to graduate 9-10k doctors a year across specialties,” he says. The growth of private medical schools and national universities pushed that to around 15k, and it could reach 25k over the next two years.

Pharmacy has a similar problem. “The pharmacy sector suffers from a structural imbalance, with years of graduate numbers exceeding actual labor-market demand,” Pharmacy Colleges Sector Head Abdel Nasser Sengab tells EnterpriseAM. He adds that the committee’s decision was taken to protect the interests of students, especially as the salaries for medical graduates continue to decline compared to newer fields like artificial intelligence.

A restructured curriculum aligned with pharma manufacturing needs, alongside expanded specialized programs that give graduates a real shot in regional and international markets, is what the supreme council calls for. “Opening new pharmacies is no longer a viable investment model amid market saturation,” Sengab says, adding that it’s a shift already pushing more pharmacy graduates toward fields like pharma manufacturing.

Many factories now pull talent from other disciplines, including agricultural colleges, to fill manufacturing roles pharmacy graduates once held. The 2023 cohort was the last to receive blanket government assignment, but 2024 and 2025 graduates were not, as new assignments shift toward actual staffing needs for a limited period.

“Any future admissions increase must track available clinical training slots and university hospital capacity,” according to Doctors’ Syndicate Chairman Osama Abdel Hay’s statement, obtained by EnterpriseAM. He warns that growing enrollment without matching hands-on training risks graduating doctors without adequate practical preparation, with implications for patient safety. The syndicate has previously called for a freeze on new medical colleges that lack properly equipped teaching hospitals. “Doctor quality starts with training quality,” Abdel Hay says, “not with higher admission numbers.”

The state’s counter-frame: The Ministry disputes the idea that training capacity is being ignored. Konsowa says Egypt’s 147 university hospitals, 52 of them specialized, already provide 30% of the country’s total healthcare bed capacity and half its ICU beds, treating around 32 mn patients in 2025 alone. The Ministry points to ongoing hospital expansions, GAHAR accreditation efforts, and expanded training programs for young medical and nursing staff as evidence it’s investing in the training side, not just tightening the admissions gate.

Status still beats salary in how Egyptian families choose majors. “Part of the fix has to be cultural,” Sengab says. Families continue steering children toward medicine for its social status, even as fields like AI, data science, commerce, and applied design offer stronger financial returns and are gradually gaining more admission seats.

Engineering wants the same treatment medicine is getting. “Admission numbers should be based on detailed studies of labor-market needs and future development plans,” Engineers Syndicate Head Mohamed Abdel Ghany tells EnterpriseAM, citing the sharp rise in engineering graduates compared with demand. The syndicate is working with research centers on labor-market gap studies and plans to coordinate with the Higher Education Ministry and the Supreme Council of Universities to align future admissions with market needs.

Reducing engineering admissions isn’t about restricting access, Abdel Ghany says, but improving training quality, narrowing the gap between student numbers and faculty capacity, and preserving public universities’ role as the backbone of Egyptian higher education.

What’s next: Watch whether Egypt uses the scoreboard again instead of a formal seat cut — it’s faster than a committee vote and it just worked. Hospital capacity either holds up against a sharper cohort, or training gaps become next season’s story.

(** Tap or click the headline above to read this story with all of the links to our background as well as external sources.)


31 August (Monday): Deadline to apply online for the Industrial Development Authority’s 540 lease-to-own industrial plots via the Egypt Industrial Hub.

SEPTEMBER

8-10 September (Tuesday-Thursday) El Alamein International Airshow, El Alamein International Airport.

10-12 September (Thursday-Saturday): Egyptian Entrepreneurship Sector Diagnostics Report Summit, El Gouna.

15 September (Tuesday): IMF to hold its eighth review of Egypt’s USD 8 bn EFF arrangement.

24 September (Thursday): Monetary Policy Committee’s sixth meeting of 2026.

27-29 September (Sunday-Tuesday): Global Conference on Population, Health, and Human Development.

28-29 September (Monday-Tuesday): Egypt Mining Forum, St. Regis Hotel New Capital.

30 September - October 3 (Wednesday-Saturday): Cityscape, Egypt International Exhibition Center, Cairo.

OCTOBER

5 October (Monday): The EnterpriseAM Egypt Forum.

6 October (Tuesday): Armed Forces Day.

10-11 October (Saturday-Sunday): Egypt Women’s Health Summit (EWHS), Cairo Marriott Hotel.

26-28 October (Monday-Wednesday): IEX Egypt, Egypt International Exhibition Center, Cairo.

29 October (Thursday): Monetary Policy Committee’s seventh meeting of 2026.

NOVEMBER

6-8 November (Friday-Sunday) : Global Entrepreneurship Festival, JW Marriott Hotel, New Cairo.

8-11 November (Sunday-Wednesday): Cairo ICT Forum.

DECEMBER

7-10 December (Monday-Thursday): Food Africa, Egypt International Exhibition Center, Cairo.

17 December (Thursday): Monetary Policy Committee’s eighth meeting of 2026.

EVENTS WITH NO SET DATE

2H 2026: Operations at Deli Glass Co’s new USD 70 mn glassware factory kick off.

2026: The Egyptian-American Economic Forum.

4Q 2026: Banque du Caire IPO.

2027

20 January-7 February: Egypt to host the African Games.

1-3 February (Monday-Wednesday): Agri Expo, Cairo International Convention Center.

April 2027: Tenth of Ramadan dry port and logistics hub to begin operations.

EVENTS WITH NO SET DATE

2027: Egypt to host EBRD’s annual meetings.

2027: Egypt-EU Summit 2027.

End of 2027: Trial operations at the Dabaa nuclear power plant expected to take place.

September 2028: First unit of the Dabaa nuclear power plant begins operations.

Now Playing
Now Playing
00:00
00:00