The real balance of power in corporate boardrooms

1

WHAT WE’RE TRACKING TODAY

A cautious return to Suez

Good morning, friends. Two stories today about the influence of industry regulations — slow-moving mechanisms that have big impacts from the boardroom to the central bank.

The first is a deep dive into boardroom power dynamics and where shareholder authority actually ends. The month of May saw three disputes that tested the limits of minority leverage: one at ERC, one at Juhayna, one at Misr Italia. Each played out differently, and together they sketch a clearer picture of how Egyptian corporate governance actually works — and how a board can out-leverage the shareholders.

The second is on the digital EGP. The CBE has moved past initial research and into proof of concept for digital currency, with a 2030 rollout broadly in view. Only three countries have launched digital currency so far, and Egypt has a long way to go. We’re pulling apart what’s real, what’s aspirational, and what the risks are for a country with a deeply entrenched cash economy.

***

ARE YOU MORE OF A LISTENER?Morning Drive is a 10-minute summary of today’s issue crafted for you to enjoy with your morning coffee, while getting the kids ready for school, or driving through the morning rush. And if you like it, tell your friends to tell their friends. They can find us on Apple, Spotify, or wherever they get their podcasts.

***

The short way home

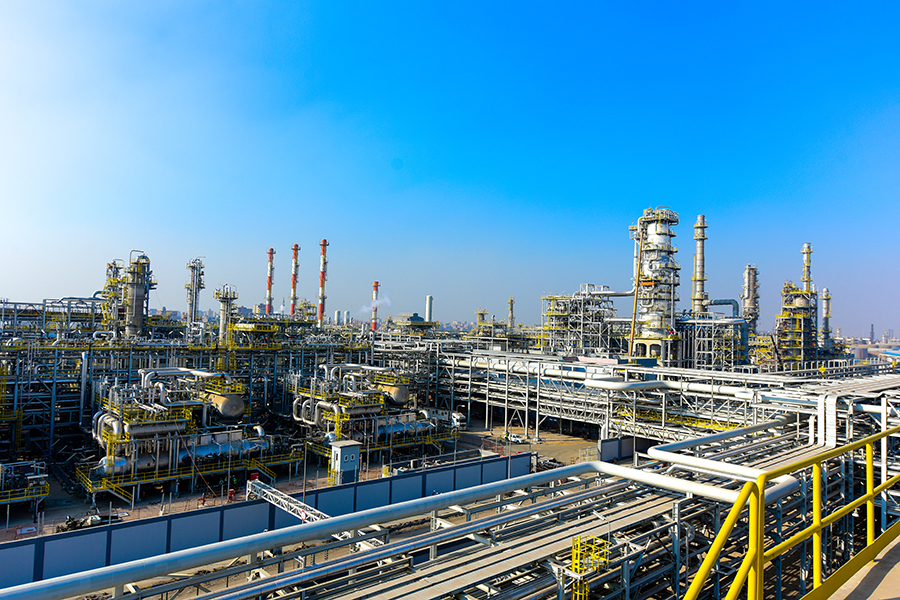
Shipping giants Maersk and Hapag-Lloyd will reroute their joint AE15 Asia-Mediterranean-Europe service through the Suez Canal instead of around the Cape of Good Hope, according to a press release. The service links ports in China, South Korea, and Malaysia with Egypt (via Port Said and Damietta) before continuing to Sri Lanka and Singapore. This puts Egyptian ports back on a direct Asia-Europe loop, rather than the longer Africa diversion, for the first time since the outbreak of the US-Israeli war on Iran.

A step, not a stampede: The carriers framed the switch as “a step towards a gradual return to the trans-Suez corridor” following a security assessment of the Red Sea — with more changes to their Gemini network in the pipeline. But the move remains conditional on continued Red Sea stability, and Maersk and Hapag-Lloyd say contingency plans to revert to the Cape route remain in place if the situation deteriorates again.

The return comes as canal revenues recover: Suez Canal revenues rose in April to their highest monthly level since February 2022. Suez Canal Authority chairman Osama Rabie said in an interview (watch, runtime: 02:00) that FY 2025/26 revenues rose 23% y-o-y to USD 4.8 bn, up from roughly USD 3.8 bn a year earlier, and transits increased 10%. That is still well below the USD 10.2 bn recorded in 2023, with the authority targeting USD 8 bn in revenues by the second half of 2027, Rabie said.

But this recovery is reversible: “Most major liner operators have only recently started cautiously reintroducing some Suez transits, and any escalation could delay or reverse that process,” Antonella Teodoro, senior transport consultant at MDS Transmodal, previously told EnterpriseAM, following the Houthis’ renewed ban on Israeli-linked vessels’ navigation in the Red Sea last month.

Region tensions have lessened, not disappeared. Earlier this week, a cargo vessel sent a distress alert saying it was under attack by unknown armed assailants 30 nautical miles southwest of Al Hudaydah, Yemen, Bloomberg reports. The UK Maritime Trade Operations (UKMTO) didn’t identify the vessel and said it was investigating, urging ships in the area to transit with caution.

Futures get a fee runway

The Financial Regulatory Authority (FRA) is discounting access to a market that hasn’t yet taken off. In setting the clearing and settlement fees for EGX futures, the regulator waived several charges for a full year — a launch subsidy the FRA chairman framed as an incentive for brokers and investors while trading is still thin, according to a statement.

Under the FRA’s board decision published in the Official Gazette, settlement services will cost 1-in-10k of transaction value (capped at EGP 5k), on top of a one-time EGP 20k clearing membership fee and an EGP 10k annual subscription — handled by Tasweyat Clearing Services, the FRA-licensed clearing house for futures.

The launch sweeteners: Several otherwise chargeable services will be waived for one year following the decision’s effective date. After that, the schedule kicks in:

  • Execution by proxy: 1-in-1k of transaction value (max EGP 5k)
  • Final contract settlement: 1-in-10k of open-position value at expiry (max EGP 5k)
  • Position transfers between settlement members: 1-in-1k of open-position value (max EGP 5k)
  • Account statements: EGP 100 each
  • Adding system users: EGP 5k/year
  • Automated connectivity to the settlement system: EGP 50k/year

Why it matters: EGX30 futures have struggled to gain traction since launching in March, with thin trading, limited market-making, and low investor familiarity holding volumes back. The EGX has already tried to make the product more legible by rolling out single-stock futures on CIB and TMG — two of the market’s most liquid names — to give investors a more familiar way to trade. While lowering operational friction won’t fix demand on its own, it readies the rails as the FRA and EGX qualify more brokerages for futures trading.

PSA-

WEATHER- It’s still hot in Cairo today, though temperatures are a bit lower, with a high of 35°C, according to our favorite weather app. The mercury is expected to inch down further to a high of 34°C over the coming two days.

It’s several degrees cooler in Alexandria, with a high of 29°C.

The big story abroad

It’s an oddly quiet Tuesday morning on the foreign front pages, with no single story dominating headlines. Among those getting top billing:

#1- Iran’s military reportedly fired at least two missiles on commercial vessels crossing the Strait of Hormuz in the early hours of the morning, two US officials told Axios. The US “is likely to retaliate with strikes against Iranian targets,” according to Axios.

#2- Vertex Pharma will acquire drugmaker Crinetics Pharma for a total equity value of approximately USD 10 bn, diversifying its access to treatments that could generate more than USD 5 bn in annual revenues. The move is the latest in a surge of pharma dealmaking, as big pharma gains confidence in navigating regulatory scrutiny while racing to offset looming patent expirations.

#3- Major banks aim to skirt limits on debit card fees: A coterie of US banks — including JPMorgan Chase, Bank of America, and Wells Fargo — are reportedly looking to bypass a federal law capping debit card fees by acquiring a network owned by the fintech player Fiserv. While these caps cost the industry bns annually, banks have long argued the limits restrict them from offering customer rewards and other services. The acquisition is still in early stages.

#4- And in the gaming world: Microsoft is letting go of 4.8k employees as part of a major restructuring of its Xbox division, as the gaming industry faces an intense hardware crisis. The company is pivoting to navigate a paradigm shift ushered in by advancements in AI.

*** It’s Going Green day — your weekly briefing of all things green in Egypt: EnterpriseAM’s green economy vertical focuses each Tuesday on the business of renewable energy and sustainable practices in Egypt, everything from solar and wind energy through to water, waste management, sustainable building practices and how you can make your business greener, whatever the sector.

In today’s issue: We unpack why Egypt’s domestic green debt market stalled after its 2020 debut, and how multilateral capital is quietly stepping in to plug the financing gap.

From Europe to Egypt: MINDSET for Sports Development brings the world’s leading youth water polo brands to Somabay this December 2026.

Featuring Habawaba, TOMO, and the new Aquatica U15 tournament, the events will welcome 1.5k participants, positioning Egypt as a premier destination for youth aquatic sports and sports tourism.

2

Enterprise explains

Corporate board games

On paper, shareholders sit at the top of the corporate hierarchy, wielding their authority through the general assembly. In practice, power doesn’t always flow the way the org chart suggests, at least not for those short of a majority. May alone saw three major boardroom disputes test the tension between formal shareholder supremacy and a board’s powers — all three were instigated by the minority side. A significant minority bloc at the Egyptian Resorts Company (ERC) exhausted every legal channel to unseat a sitting board and failed, while Baladna’s 16% stake in Juhayna failed to buy it a board seat. Meanwhile, two co-founding brothers at Misr Italia — the only unlisted company in this piece — deadlocked over control until a negotiated buyout was the only way out.

The architecture of power

The Companies Law (pdf) grants shareholders — collectively, through the general assembly — exclusive authority over some of the business’s most consequential decisions, including capital structure changes, auditor appointments, related-party transaction approvals, and extraordinary resolutions. To carry them out, they elect a board of directors to act on their behalf between meetings. The board accumulates institutional continuity and operational knowledge. But the shareholder base, especially a diffuse one, is harder to mobilize — that’s why an individual shareholder’s formal ranking above the board doesn’t automatically translate into leverage.

“In practice, some companies, especially those without an absolute majority, rely more on the policies and decisions of the board,” Islam Saeed, Founding Partner of Alphalex Legal and Tax Firm, tells EnterpriseAM. “The general meeting’s role becomes mainly two things: board elections from time to time, and the annual meeting.”

The exception is concentrated ownership structures, such as a single dominant shareholder or shareholders organized into blocks — think private equity. In those cases, formal authority and effective control are largely the same thing — the controlling block directs the assembly, the assembly elects a sympathetic board, and the board runs the company accordingly. None of the three May disputes involve that kind of shareholder, which is exactly why each had to be resolved the hard way.

Beneath the Companies Law sit executive regulations that fill in procedural detail, and beneath those, the company’s articles of association — mostly a General Authority for Investment and Free Zones (Gafi) template that listed companies can customize within narrow limits. “Currently, it is still very conventional compared to other jurisdictions,” Saeed says. Layered on top are Financial Regulatory Authority (FRA) and Gafi corporate governance rules and minority protection guidelines. Adhering to all of it can “significantly minimize or even eliminate disputes over procedural matters,” leaving only the substantive ones, Saeed argues.

Formal power, effective control

Board members can disnesent, but they can’t veto. A single member of an EGX-listed company’s board can disagree and document it but cannot block a decision that has enough votes behind it, nor go to a regulator to reverse it unilaterally. “While any board member technically has the right to object, if a legally valid approval is reached without them, and as long as the procedures were executed carefully, lawfully, and in compliance, they do not have the right to obstruct the matter or turn to any authority to reverse it,” Saeed explains. Collectively, the board has more room: members who think a decision goes against the company’s interests can ask the chairman to escalate to the general assembly, or take concerns to Gafi or the FRA if they hit a wall internally. But majority still rules.

Shareholders operate on a different track. Their first stop is the general assembly: a shareholder who believes the company has acted improperly can formally notify the chairman and demand the issue be addressed. Investors holding certain ownership thresholds (typically 5% to 10%) can call a meeting themselves or force items onto an annual general meeting (AGM) agenda. Only after those internal channels have been exhausted can the dispute move outside the company — and even then, shareholders must prove legal standing and a direct interest in the outcome.

Wearing two hats changes the math. A board member who also holds equity has two separate tracks available at once, Saeed says. That dual standing matters in a dispute: they have direct visibility into board decisions as they’re made, can object on the record in real time, and can simultaneously mobilize their shareholder rights to force the matter to the general assembly.

Shareholders overplay

ERC is the clearest illustration of the escalation ladder hitting its ceiling. A minority bloc holding 24.95% of ERC ran through every available channel after failing to unseat the sitting board at a September 2025 general assembly — four court petitions, four rejections. They turned to Gafi, which called a new board election. The Administrative Court blocked it in four days, finding Gafi had no legal basis to intervene.

The rapid response was unusual. “Expecting a standard judicial response within days for regular corporate disputes is unrealistic,” Saeed tells us, arguing that what made ERC different was irreversibility. For a judge to grant an urgent interim motion, two conditions must be met — immediate necessity and a strong prima facie legal justification, Saeed says. ERC cleared both bars: installing a new board, once done, would have been nearly impossible to undo, and Gafi had failed to follow the correct statutory sequence. The general assembly’s decision was never really in question here — the real question was whether a regulator could reopen a fight the bloc had already lost in court.

Juhayna makes a different point — a stake doesn’t automatically mean a seat. Baladna, the Qatari dairy company, has been upping its stake in Juhayna since 2022 to around 16% — the second-largest on the cap table. However, the Companies Law bars a candidate involved in a competing business from standing for the board without explicit general assembly approval, and that bar applies regardless of ownership size. “The shareholders evaluate whether the state of conflict is manageable under certain restrictions or completely unmanageable,” Saeed says. A controlling shareholder can override the bar through the assembly, but a minority shareholder cannot. And in Juhayna’s case, the assembly hadn’t granted it, and the Cairo Economic Court upheld the exclusion.

When the law runs out of road

The two co-founding brothers of Misr Italia deadlocked over control of one of Egypt’s largest unlisted real estate developers until no legal mechanism could produce a resolution either side would accept. “A dispute usually boils down to one party being legally in the right and the other in the wrong,” Saeed says — but when the split is close enough that neither side can establish that cleanly, the market finds its own way. Gafi’s Investors Disputes Settlement Center brokered the exit: Khaled El Assal bought his brother Hani’s 49.9% stake for EGP 1.42 bn and walked away with full ownership.

The pattern underneath

Taken together, the three cases suggest minority shareholders’ leverage is situational, depending on the type of dispute and type of company. In the case of ERC, shareholders had regulatory and judicial avenues to challenge the board, albeit with clear limits. In Juhayna’s case, a statutory threshold trumped the size of the stake. For Misr Italia, with no institutional channel to fall back on, the dispute ultimately came down to a negotiated exit.

What’s next

A pending overhaul could reshape this terrain. Proposed amendments to the CompaniesLaw, approved by a joint Senate committee last month, would strip boards of one of their sturdiest procedural levers: the ability to stall a general assembly simply by not meeting quorum. Under the current law, an assembly can’t validly convene without a minimum number of board members present — a threshold some boards have used to delay or dodge shareholder scrutiny. If passed, assemblies could proceed and exercise full powers once shareholder quorum is met, with absent directors facing fines instead. The package still needs a full Senate vote and House approval before reaching the president’s desk, with no timeline yet for the executive regulations that would fill in the details.

This publication is proudly sponsored by

3

Economy

Slow, but steady

The Central Bank of Egypt (CBE) is quietly laying the groundwork for what could become its most ambitious monetary project yet — the digital EGP (e-Pound). As central bank digital currencies (CBDCs) move from concept to reality globally, Egypt is weighing the promise of financial inclusion and efficient government payments against cybersecurity risks, banking sector stability, and a deeply entrenched cash economy.

Where things stand: The CBE completed its initial research phase and moved on to proof of concept, with an official rollout broadly targeted for 2030. That timeline is anchored in a 2024 cabinet IDSC roadmap, which tethers the e-Pound to a state mandate of achieving 100% financial inclusion and expanding active e-wallets to 80 mn by the end of the decade.

It’s not crypto

Digital currency is different from cryptocurrency. Digital tokens like BTC are not issued or backed by any government or central bank. If launched, “the digital EGP would be an official digital form of the national currency issued directly by the central bank,” digital economy expert Mai Hegazi explains.

It’s also not the same as mobile payment apps like Vodafone Cash or Fawry. “These types of electronic wallets are merely intermediaries managed by banks or telecom companies to store traditional cash and facilitate its transfer,” Sayed Kasem, a member of the Egyptian Society for Political Economy and Legislation, explains. Digital currency is a new system, and it has not seen widespread adoption — yet.

Moving cautiously

Globally, CBDC development remains uneven. While 146 countries are actively exploring digital currencies and 77 have reached advanced research, pilot, or launch stages, complete public retail rollouts remain rare. Only three countries have completed them — the Bahamas, Jamaica, and Nigeria — according to the Atlantic Council’s CBDC tracker.

“Not every digital step means progress; some projects do not just test technology, but rather test the readiness of the economy itself,” financial analyst Hany Abou El Fotouh tells EnterpriseAM. “Does Egypt need a digital currency issued by the CBE now, or is the calmer and more realistic priority to strengthen the existing payments infrastructure before moving to a more sensitive tool?”

The CBE’s measured pace reflects strategy, not hesitation. “The CBE treats the digital EGP project as a long-term strategic initiative linked to the future of the monetary system, not just as a new payment tool,” AASTMT economics professor Shaimaa Wagieh says. “The CBE is currently focusing on studying international models […] before moving into the actual implementation phase,” she adds. EG Bank board member Mohamed Abdel Aal notes that financial market volatility and regional geopolitical challenges also slowed the project’s early execution.

Lessons from abroad

The CBE is drawing lessons from Gulf initiatives as well as retail CBDC pilots in India and Nigeria. For the UAE and Saudi Arabia, the focus has largely been wholesale payments and cross-border settlements between the two states — through Project Aber — rather than replacing cash. “The importance of Project Aber lies not only in the technical aspect, but in the fact that it proved the feasibility of using CBDCs to settle cross-border payments between two countries more efficiently,” Wagieh says.

Another multilateral project, mBridge, explores a wider experiment — including the Central Bank of the UAE, the Bank for International Settlements, Innovation Hub Centre in Hong Kong, the Hong Kong Monetary Authority, the Bank of Thailand, and the Digital Currency Institute of the People’s Bank of China. “The most important lesson for Egypt here is that digital currencies may not be just a local payment method but a tool to enhance the efficiency of international trade, investment, and remittances,” Wagih adds.

India and Nigeria offer retail lessons: India has seen success with its experiment, but this is due more to the advanced digital environment that preceded the digital currency, rather than the new system itself, Wagieh explains. And the environment is key — Nigeria launched eNaira relatively early but failed to reach target usage levels because users were more comfortable using pre-existing forms of digital payment, Wagieh notes. Ultimately, “the success of the digital EGP will depend entirely on the added value it will offer to citizens compared to solutions already available,” she says.

The pros

The digital EGP could improve payment efficiency, reduce cash handling costs, strengthen financial inclusion, and help formalize parts of Egypt’s large informal economy — if it’s implemented successfully. “Unlike paper cash, the digital EGP will provide an accurate record for every financial transaction,” Kasem says. Wagieh notes that “cash subsidies and social transfers can be directed straight to beneficiaries instantaneously, securely, and traceably. Leakage rates can be minimized, and targeting can be improved.” Meanwhile, the currency could even become “programmable money,” directing funds to specific purposes according to regulatory controls, according to Hegazi.

The risks

The biggest challenge is ensuring that a retail CBDC strengthens rather than disrupts the banking system. “If a portion of deposits shifts to the digital EGP, the banks’ ability to lend could be affected,” Wagieh warns. Therefore, many central banks are designing CBDCs to complement commercial banks rather than compete with them.

Cybersecurity and privacy: Kasem describes cybersecurity as “the essential pillar for the success and stability of launching the digital EGP.” Abou El Fotouh, however, says there are additional risks to consider as well. “There are questions regarding privacy, transaction traceability limits, and whether the commercial banks will still have a role if citizens have a direct payment tool linked to the central bank,” he says.

OUR TAKE- The digital EGP is a monetary reform, not a tech project. The CBE should resist rushing into a retail launch, focusing instead on wholesale settlements and strengthening the existing payment ecosystem. As Wagieh notes: “The digital EGP represents the next stage of evolution, not the starting point.”

4

A MESSAGE FROM VISA

Who should protect online shoppers? The answer is institutional

Egyptian online shoppers expect institutions to lead on fraud protection. Visa’s Stay Secure 2026 study found that 47% place primary responsibility with government authorities or regulators, followed by banks and financial institutions at 43% and payment providers at 28%.

Personal responsibility sits much lower. Only 13% say shoppers themselves should hold primary responsibility. Awareness still matters, but the broader expectation is clear: institutions in digital commerce are expected to shoulder more of the protection burden.

Reassurance also has a clear shape. The study found that 64% would feel secure receiving real-time alerts from their bank or payment app when something looks suspicious. Another 44% would feel more comfortable seeing a familiar, trusted logo at checkout.

For banks, merchants, payment providers, and regulators, the message is direct. Fraud protection needs to be visible while people are paying, not confined to awareness campaigns. The clearest proof points in the study are real-time alerts and trusted logos at checkout.

Secure payments have always mattered. The shift lies in how clearly shoppers assign responsibility — and how closely they connect reassurance to the moment they decide whether to complete an online purchase.

5

Also on our Radar

Checking in at Wadi Yemm

Hassan Allam tapped for Montage Ras El Hekma: Modon Ras El Hekma — the local arm of Abu Dhabi’s Modon Holding — awarded Hassan Allam Construction the contract to build the Montage Hotel & Branded Residences at Ras El Hekma, according to a statement (pdf). The project features a 200-key Montage-branded hotel, 96 branded residence villas, a clubhouse, and supporting infrastructure in Wadi Yemm. The award builds on a November 2024 MoU between Hassan Allam and Modon to cooperate on infrastructure, energy, and water and wastewater treatment projects at the coastal megaproject.

A growing footprint: The Montage project marks Hassan Allam’s third major mandate at Ras El Hekma, alongside its ongoing work on the 17-kmRing Road and dry bulk excavation for the 5.3-km Grand Canal.

Pension pot

KafIns.’ pension assets under management (AUM) have topped EGP 1 bn a little over a year after launch, the EFG Finance-GB Corp JV said in a statement (pdf). The company expects pension AUM to approach EGP 2 bn by the end of this year, helped by employer adoption and a planned Pension V2 rollout — the next phase of its pension platform — that will add individual top-ups, new investment options, and life ins. Pension revenues hit EGP 600 mn in 2025, accounting for roughly half of the company’s total top line, which exceeded EGP 1.2 bn.

REMEMBER- Kaf launched its digital pension platform last year, targeting corporates and employees with contribution tracking, investment-return visibility, and HR dashboards.

6

PLANET FINANCE

Asian dry up

16 years — that’s how long it’s been since Asia’s loan market had a first half this bad. USD, EUR, and JPY loan issuance across Asia Pacific ex-Japan dropped 15% y-o-y to USD 69 bn in 1H 2026, the weakest first-half performance since 2010, according to Bloomberg data. The second half also looks no better.

The Iran war is the primary culprit. The conflict has stalled investment activity and pushed out financing timelines, with lenders applying more scrutiny to every transaction. “With increased uncertainty, there is a reduction in corporate confidence,” Andrew Ashman, head of Asia Pacific loan syndicate at Barclays, told the business information service. The M&A-driven issuance banks had expected hasn’t shown up, and the geopolitical drag looks set to last through year-end.

The Middle East liquidity channel is also narrowing. Middle Eastern banks are pulling back from offshore syndications and directing liquidity to their domestic markets — cutting off a funding source Asian borrowers have relied on for years. HSBC’s Ashish Sharma, head of leveraged and acquisition finance for Asia Pacific, expects the corridor to recover eventually — but not before conditions stabilize.

Some of that capital is landing in Australia. Loan volumes there fell around 10% in 1H, but an influx of Middle Eastern capital — redeployed as banks treat Australia as a safe haven — has intensified lender competition and compressed margins, Gavin Chappell, global head of acquisition finance and syndication at ANZ, told Bloomberg.

But it’s not just the war. China’s property slump is still weighing on credit demand, Indonesia’s regulatory tightening has cooled corporate appetite, and higher oil prices, paired with weaker currencies, have tightened conditions in markets like India.

Don’t expect the second half to look different. “The second-half volume may not be different from the first half purely because of macroeconomic reasons,” Birendra Baid, head of Asia Pacific loan syndication at Deutsche Bank, said. Still, with banks still willing to lend, pricing is expected to compress.

Where the money is going instead: With conventional volumes muted, capital is rotating toward higher-yielding pockets. Structured credit is picking up the slack, offering better returns than conventional corporate loans.

Data centers are the exception. Recent transactions include DayOne Data Centers Singapore doubling a MYR 15 bn facility, Blackstone-owned AirTrunk closing a USD 2.3 bn loan for a Malaysia project, while also seeking a USD 3 bn facility for a Sydney data center. Margins are rising too — a recent Malaysia transaction priced at 310 bps over SOFR, up from levels largely in the 200s over the past year, with bankers expecting another 20-50 bps of spread widening as further transactions come to market.

MARKETS THIS MORNING-

Asia-Pacific markets are down in early trading, with South Korea’s Kospi leading losses, down over 5%. Japan’s Nikkei is down almost 1%. Over on Wall Street, stocks are set to open flat with futures little changed.

EGX30

52,503

+2.7% (YTD: +25.5%)

USD (CBE)

Buy 48.79

Sell 48.93

USD (CIB)

Buy 48.75

Sell 48.85

Interest rates (CBE)

19.00% deposit

20.00% lending

Tadawul

10,813

+0.1% (YTD: +3.1%)

ADX

9,922

+0.2% (YTD: -0.7%)

DFM

6,091

+0.5% (YTD: +0.7%)

S&P 500

7,537

+0.7% (YTD: +10.1%)

FTSE 100

10,652

-0.3% (YTD: +7.3%)

Euro Stoxx 50

6,398

-0.2% (YTD: +10.4%)

Brent crude

USD 72.23

+0.3%

Natural gas (Nymex)

USD 3.26

+0.3%

Gold

USD 4,158

-0.2%

BTC

USD 64,325

+1.0% (YTD: -26.6%)

S&P Egypt Sovereign Bond Index

1,076

+0.3% (YTD: +8.3%)

S&P MENA Bond & Sukuk

152.23

+0.1% (YTD: +0.2%)

VIX (Volatility Index)

15.57

-1.5% (YTD: +4.2%)

THE CLOSING BELL-

The EGX30 rose 2.7% at yesterday’s close on turnover of EGP 12.2 bn (40.8% above the 90-day average). Local investors were the sole net buyers. The index is up 25.5% YTD.

In the green: E-finance (+9.0%), Fawry (+5.3%), and Raya Holding (+4.7%).

In the red: Orascom Construction (-2.3%), Qalaa Holdings (-1.4%), and AMOC (-1.2%).

7

Going Green

Rules without market

Framework, no flow: Five years after the government’s USD 750 mn sovereign green bond debut — and three years after a promised USD 500 mn follow-on that never materialized — cumulative green and sustainability-linked issuance in Egypt sits at just USD 1.45 bn. As we flagged last week, Egypt has the framework for a green debt market without a market. Bankers and sustainability experts we spoke to converge on why.

The rulebook was never the problem, sources tell us. What’s strangling the market is punishing borrowing costs, a currency that’s made every USD-denominated issuance harder to justify, and a pipeline of bankable projects too thin to bring to market — a combination that reshaped issuers’ priorities long before it hit green debt specifically.

REMEMBER– Since the 2020 sovereign debut, the market has produced three transactions of scale: CIB’s USD 100 mn corporate green bond in November 2021, taken in full by the IFC; the Arab African International Bank's USD 500 mn sustainability bond, IFC subscribed to the bond with USD 300 mn while the European Bank for Reconstruction and Development (EBRD) and British International Investment invested some USD 100 mn each; and Banque Misr’s USD 100 mn sustainability-linked loan in July 2024, arranged by EBRD and tied to social performance targets. Each of the three needed a development finance institution to get to market.

The promised USD 500 mn green bond follow-on for 2023 never came. The Finance Ministry is still waiting on an African Development Bank guarantee to unlock a new framework and USD 500 mn in green samurai bonds, a senior government official told EnterpriseAM last November. Egypt has borrowed abroad three times since — but never in green.

The macro backdrop: Non-equity issuance — corporate bonds and securitization combined — fell 36.2% in 2024, according to data released by the Financial Regulatory Authority (FRA), as the Central Bank of Egypt’s benchmark rate climbed from 9.75% in March 2022 to 27.75% in March 2024. It’s not a green-market problem specifically, this is what happens to debt issuance of every kind when borrowing costs nearly triple in two years. “When interest rates reached around 27%, no issuer was willing to issue a 10-year bond in EGP,” environment and energy expert Moustafa Mourad tells EnterpriseAM. “At the same time, issuing in USD became considerably riskier because of exchange-rate volatility.”

The regulatory frame isn’t what's holding it back. “The framework is already in place, but the challenges relate to pricing and the high cost of funding,” financial analyst Mohamed Abdel Moneim tells us, referring to the FRA’s carbon and sustainable finance framework, first launched with green bond guidelines in 2018 and expanded since, alongside the Finance Ministry's 2022 Sovereign Sustainable Financing Framework. Abdel Moneim points to five compounding factors: higher rates, corporates deferring long-term financing, a thin pipeline of issuance-ready projects, and the cost of preparing green frameworks and obtaining independent external opinions.

Not to mention, the CBAM overhang. “The uncertainty surrounding the EU's Carbon Border Adjustment Mechanism has also contributed to slower issuance, particularly for exporters that are still assessing its long-term implications,” Hesham Eissa, environmental science and climate change analyst and DCarbon Global board member, adds.

Meanwhile, SLLs are picking up the slack. “Sustainability-linked loans have become more attractive because they are simpler, less costly, more flexible, and do not require proceeds to be allocated to specific green projects,” Abdel Moneim says. AASTMT economics professor Shaimaa Wagieh says banks are increasingly favoring SLLs while waiting for issuance conditions to improve — quicker to execute, linked to measurable KPIs, and cheaper than public debt.

All four sources we spoke to agree on the market’s biggest structural weakness: too few projects are ready for capital-market financing. “There are good projects, but not all of them are ready to be financed through the capital market,” Abdel Moneim says. “We need to develop a larger green pipeline, particularly in renewable energy, clean transport, desalination, waste management, and green buildings.” Financing itself isn’t the constraint, EG Bank board member and veteran banker Mohamed Abdel Aal — the market lacks projects meeting the environmental, technical, and financial standards issuance requires. Eissa adds Egypt needs more technical expertise to structure bankable green projects, particularly in green buildings.

Green bonds carry costs conventional debt doesn’t. Second-party opinions, external verification, ongoing reporting — the premium alone is enough to push issuers who can borrow conventionally to do so, Mourad says. In a market where the underlying cost of capital has already tripled, the additional green premium is doing double damage.

DFIs are still the market. “There is growing interest in this type of financing, but it remains limited compared to international financial institutions, which continue to represent the largest investor segment,” Abdel Moneim tells us. Mourad names them specifically: IFC, EBRD, and the African Development Bank. One reason domestic demand remains shallow, he argues, is the absence of incentives — or requirements — for local institutional investors to allocate part of their portfolios to sustainable debt instruments. Wagieh argues investment funds, insurers, and pension funds will need to play a much larger role if the market is to deepen.

A new sovereign bond could reset the benchmark, but won’t be enough on its own. “It would establish a pricing benchmark for corporate issuers, restore foreign investor confidence, and help reactivate the domestic market,” Mourad says. Wagieh agrees but adds the counterweight: a sovereign issuance alone doesn't fix a structurally stuck market. “A sustainable market also requires a stronger pipeline of bankable projects, greater private-sector participation, a broader investor base, and incentives that encourage issuers to come to market,” she adds.

Abdel Aal offers the softest reading of the market: “Rather than facing a crisis, the sustainable debt market is undergoing a strategic repositioning in response to evolving global and domestic economic conditions.” His closing view is more diagnostic than the framing suggests. “The future of Egypt's sustainable debt market depends less on launching another transaction than on moving from isolated deals to a sustainable market ecosystem,” he says.

Our take: The consensus is striking: the framework works, the macro doesn't, and the pipeline isn't ready. Egypt has closed three sustainable finance transactions of scale since its 2020 sovereign debut, each leaning on a development finance institution to get there. The pattern we read says less about appetite, and more about timing. The promised USD 500 mn green bond follow-on still hasn’t materialized, and another sovereign green issuance could reset the benchmark. But until the cost of capital eases, isolated deals will remain the market’s default, not its exception.


JULY

9 July (Thursday): Monetary Policy Committee’s fourth meeting of 2026.

23 July (Thursday): Revolution Day (TBC).

AUGUST

19 August (Wednesday): Connected Banking Summit, Fairmont Nile City Hotel.

20 August (Thursday): Monetary Policy Committee’s fifth meeting of 2026.

26 August (Wednesday): Prophet Muhammad’s birthday.

SEPTEMBER

8-10 September (Tuesday-Thursday) El Alamein International Airshow, El Alamein International Airport.

10-12 September (Thursday-Saturday): Egyptian Entrepreneurship Sector Diagnostics Report Summit, El Gouna.

15 September (Tuesday): IMF to hold its eighth review of Egypt’s USD 8 bn EFF arrangement.

24 September (Thursday): Monetary Policy Committee’s sixth meeting of 2026.

27-29 September (Sunday-Tuesday): Global Conference on Population, Health, and Human Development.

OCTOBER

6 October (Tuesday): Armed Forces Day.

10-11 October (Saturday-Sunday): Egypt Women's Health Summit (EWHS), Cairo Marriott Hotel.

26-28 October (Monday-Wednesday): IEX Egypt, Egypt International Exhibition Center, Cairo.

29 October (Thursday): Monetary Policy Committee’s seventh meeting of 2026.

NOVEMBER

6-8 November (Friday-Sunday) : Global Entrepreneurship Festival, JW Marriott Hotel, New Cairo

DECEMBER

7-10 December (Monday-Thursday): Food Africa, Egypt International Exhibition Center, Cairo.

17 December (Thursday): Monetary Policy Committee’s eighth meeting of 2026.

EVENTS WITH NO SET DATE

July 2026: British Prime Minister Keir Starmer set to visit Egypt.

2H 2026: Operations at Deli Glass Co’s new USD 70 mn glassware factory kick off.

2026: The Egyptian-American Economic Forum.

4Q 2026: Banque du Caire IPO.

2027

16-18 January (Saturday-Monday): Agri Expo, Cairo International Convention Center.

20 January-7 February: Egypt to host the African Games.

April 2027: Tenth of Ramadan dry port and logistics hub to begin operations.

EVENTS WITH NO SET DATE

2027: Egypt to host EBRD’s annual meetings.

2027: Egypt-EU Summit 2027.

End of 2027: Trial operations at the Dabaa nuclear power plant expected to take place.

September 2028: First unit of the Dabaa nuclear power plant begins operations.

Now Playing
Now Playing
00:00
00:00