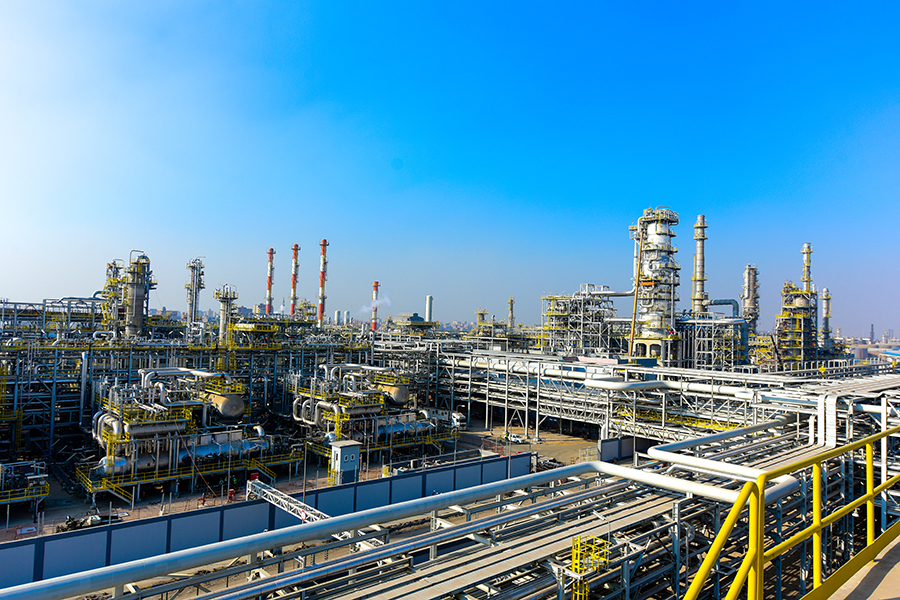
Fawry’s TPA license places it between patients, providers, and payers

1

WHAT WE’RE TRACKING TODAY

House signs off on FY 2026/27 budget

Good morning, ladies and gents. It’s a quieter morning as Egypt continues to ride high from yesterday’s knockout performance at the World Cup, but we have three pieces worth your time.

Fawry has a TPA licence — and the pricing trap that has caught existing firms is the one its model is built to avoid. We spoke to several industry players to get a full read on where the third-party administrator licence puts Fawry between patients, providers, and payers.

In other news, the government is moving to narrow the planned 14% VAT on leased office space, three officials tell us — potentially keeping factories and buildings providing direct services to citizens outside the net.

You don’t want to miss our deep dive in Going Green. A mandatory carbon market is meeting an exchange that has seen only six trades in 22 months, with credits at 17x global rates and brokers required. We have the full read, with insight from industry insiders, in the news well, below.

***

ARE YOU MORE OF A LISTENER?Morning Drive is a 10-minute summary of today’s issue crafted for you to enjoy with your morning coffee, while getting the kids ready for school, or driving through the morning rush. And if you like it, tell your friends to tell their friends. They can find us on Apple, Spotify, or wherever they get their podcasts.

***

Budget clears the House

The House of Representatives gave its final nod to the FY 2026/27 budget and development plan, sending the Planning and Budget Committee’s recommendations to the government for implementation after two weeks of plenary debate, according to a statement.

What MPs want fixed: Drafted before the regional war escalated, the budget banks on an exchange rate of EGP 47 to the USD and oil at USD 75 per barrel. MPs are requesting more realistic assumptions based on actual execution rates, alongside strict adherence to constitutional spending minimums.

Tighter fiscal governance: Lawmakers want a durable general tax law rather than relying on piecemeal tax facilitation packages and are asking for a seat at the table during early “public consultations” for future financial legislation. The committee is also pressing the government to tighten oversight on customs exemptions, finalize the AI-driven property-tax digitization, submit the approved medium-term budget framework annually, and close loopholes in the state wage-ceiling system.

REMEMBER- The draft budget was referred to the House in April, with the government targeting EGP 4 tn in revenues, EGP 5.1 tn in spending, EGP 3.5 tn in tax receipts, a 5% primary surplus, and a 4.9% overall deficit. The bigger fiscal story is still the same: Finance Minister Ahmed Kouchouk has been promising no new taxes while leaning on base-broadening, compliance, and follow-up tax packages to lift revenues.

A clean break

The new company being carved out of Ghazl El Mahalla will be launched next month, and the government will begin receiving offers from interested investors, State-Owned Companies Unit head Hashem El Sayed tells EnterpriseAM. The company will house new factories — which were built under a state-backed EGP 35 bn modernization program — and could either be offered to a strategic investor or listed on the EGX, El Sayed says.

Dividing the company into two entities is meant to separate the new capacity from the legacy burden. The first entity is a leaner newco with upgraded factories and a limited workforce, and the second is the legacy company that will undergo a separate restructuring. The original company carried heavy liabilities, making it difficult to reel in local and foreign capital — the split will make the new company more investable, El Sayed explains. The new company is also expected to be the world’s largest spinning company by capacity, he says.

IN CONTEXT- El Sayed told us in April that Ghazl El Mahalla could be split into two companies. The split — which he tells us only took three months to execute — is part of the government’s wider push to make it easier for the private sector to enter public assets, either through strategic stake sales, EGX listings, or management through the Sovereign Fund of Egypt. The government is also keeping the door open to strategic sales if offers match fair-value studies.

ALSO- Four more state-owned companies are set to be registered on the EGX this week, El Sayed says. Oil-sector offerings will also continue through the summer, with investment banks being appointed for the transactions, he adds. El Sayed had already informed us earlier this month that a government committee was expected to approve the temporary listing of four oil companies as the privatization pipeline tries to regain momentum to reach its USD 4.5 bn proceeds target over the next three years.

Blurring public lines

The Egypt Healthcare Authority (EHA) is eyeing an EGX listing for Green Lotus, Al Mal reports, citing an unnamed government official. The new investment arm is still in the process of being set up, and the authority is aiming to get it off the ground before year-end — ahead of the IPO — though details around the size and timeline of the offering remain under wraps. Green Lotus is expected to serve as the authority’s commercial and investment vehicle, helping to bring in private-sector partners and channel capital into healthcare assets and investment funds, the official says.

ICYMI- The move comes as the EHA lays the groundwork for institutional backing, recently signing a protocol with the Financial Regulatory Authority to develop sustainable healthcare financing models. The government has been expanding private participation in healthcare well beyond Green Lotus. We reported in February that the pipeline of private-participation prospects has grown to 62 projects, up from seven, spanning flagship hospitals including Sheikh Zayed Specialized and Galala.

Back up to speed

Gas flows from Israel’s Tamar and Leviathan fields to Egypt rose 17% over the past few days to 1 bcf / d, following a temporary dip to an average of 850 mmcf / d tied to routine maintenance at both fields, Al Arabiya reports, citing an unnamed government official.

The status: Israeli gas now covers some 15% of our daily gas needs, even as the Oil Ministry pushes new exploration and brownfield development at existing fields to lift domestic output. Local production currently sits at around 4 bcf/d against consumption exceeding 6.7 bcf / d — a daily deficit of roughly 2.7 bcf / d that will widen as summer electricity demand peaks.

New Arab League chief

Former Foreign Minister Nabil Fahmy has been appointed secretary-general of the Arab League, succeeding Ahmed Aboul Gheit, according to a Foreign Ministry statement. Fahmy’s five-year term will begin 1 July.

PSA-

WEATHER- It’s another warm day in Cairo today, though it may get foggy in the early morning , with a high of 34°C and a low of 23°C, according to our favorite weather app.

It’s nicer in Alexandria, with a high of 29°C and a low of 21°C.

The big story abroad

There appears to be some headway on the US-Iran front, as Washington temporarilyauthorizes Tehran to sell oil in USD for two months — a move US Vice President JD Vance noted coincides with Iran's agreement to grant inspectors access to its nuclear sites. The Iranian Foreign Ministry denied the claim.

Meanwhile, UK Prime Minister Keir Starmer announced he is stepping down, potentially setting the stage for Labor Party frontrunner Andy Burnham, who was sworn in as an MP last week. A timetable outlined by Starmer could see Burnham take office by 17 July, becoming the country’s seventh leader in ten years.

SpaceX has good news… Rocketmaker and AI player SpaceX locked in a computing power agreement worth up to USD 6.3 bn with open-source AI startup Reflection, which will pay Elon Musk’s company USD 150 mn per month to access its Colossus 2 data center. This follows similar computing power-related plays with giants of the US AI scene, namely Anthropic, Google, and Cursor.

…and bad news: SpaceX lost USD 400 bn in market value, a twist of fate after its landmark debut on Wall Street. The dip was part of a wider tech selloff triggered by expectations that the Federal Reserve will hike rates as soon as September — US government bond yields climbed sharply.


*** It’s Going Green day — your weekly briefing of all things green in Egypt: EnterpriseAM’s green economy vertical focuses each Tuesday on the business of renewable energy and sustainable practices in Egypt, everything from solar and wind energy through to water, waste management, sustainable building practices and how you can make your business greener, whatever the sector.

In today’s issue: We unpack why the Financial Regulatory Authority was forced to grant NBFIs a six-month lifeline on mandatory carbon reporting, revealing how the Egyptian Climate Exchange functions less like a transparent market and more like an illiquid, overpriced black box.

2

Companies

One licence, three roles

Fawry secured a Third-Party Administrator (TPA) licence through a new subsidiary, Treemed TPA, that will “operate as the backbone of Fawry Healthcare,” the company said in a press release last month. The fintech platform has been quietly building toward healthcare administration for several years by acquiring entities in medical services management and launching an ins. company, CEO Ashraf Sabry tells EnterpriseAM.

Behind the new brand: Fawry Healthcare will manage ins. claims, administer provider networks, process digital healthcare payments, and use data analytics for fraud detection and claims leakage prevention. The strategy is one of ecosystem integration rather than a standalone business, Sabry says. “Fawry differentiates between platform services and direct end client products,” he says. “The TPA will work with other ins’ers. Service providers can use our health technology solutions and we can integrate our TPA into their platforms.”

SOUND SMART- A TPA sits between an ins. company/provider and the healthcare system. It doesn’t carry ins. Risk — it manages the program: processing claims, verifying eligibility, running provider networks, and authorizing procedures. The company or provider underwrites while the TPA operates, earning a service fee, not a share of premiums. What makes TPA control significant is the data: a TPA that manages claims sees every transaction between patient, provider, and payer.

The regulatory backdrop

Companies performing TPA functions in Egypt previously operated outside direct Financial Regulatory Authority (FRA) oversight — managing healthcare programs for ins. companies and corporates without being subject to the same rules that govern the ins. companies themselves. A source at the FRA tells EnterpriseAM that this created structural and cumulative problems. Some companies were assuming ins. risk — covering treatment costs directly for companies and unions — without holding the technical reserves required to back those liabilities. Others operated with no binding standards on approval speeds, complaint handling, or data confidentiality. The FRA concluded that bringing TPAs under its supervision was necessary to protect the financial stability of the system and the rights of policyholders, the source tells us.

The new framework was established under the Unified Ins. Law No. 155 of 2024. Under it, a licensed TPA cannot design and sell ins. programs directly to the public or carry financial risk without a licensed ins. company behind it. Disputes are now governed by FRA Board Resolution No. 77 of 2025, which requires companies to establish complaint units and gives policyholders a path to escalate to the FRA directly.

The pricing squeeze

Fawry is entering a sector under acute financial stress. The core problem is a pricing trap the new regulatory framework does not address, TPA operator Tricare ’s Chairman Mohamed Abdelgany tells EnterpriseAM. TPAs are contractually obligated to deliver services at fixed prices for the duration of a contract, while hospitals and laboratories raise their fees mid-year with no regulatory constraint. “I am obligated to deliver the service — but the one selling me the service is the one who raised the price, not me,” Abdelgany tells us. He gives a specific example: a consultation fee at one major hospital rose from EGP 450 to EGP 750 and then to EGP 1.2k within the same contract year. Multiplied across 37k clients, he says, the price difference becomes mns of EGP in losses absorbed entirely by the TPA.

The safety valve that previously allowed TPAs to pass excess costs to clients — known as a stop-loss mechanism — was abolished by the FRA. Abdelgany says the authority has also declined to regulate provider pricing directly on the grounds that hospitals fall under the Health Ministry’s jurisdiction, not the FRA’s. That leaves TPAs caught between fixed-fee contracts and unregulated provider inflation, with no mechanism to recover the difference.

Fawry’s model appears structured to avoid this trap. Fawry’s licence focuses on the technical administration of ins. programs, with pricing risk sitting with ins. companies rather than with Treemed TPA, Abdelgany says. That means Fawry targets administrative service fees while remaining insulated from the provider pricing volatility that is squeezing existing operators. Whether that model solves the sector’s structural cost problem — or simply sidesteps it — is a question the company has not yet answered.

The pitch

The commercial logic starts with a structural problem Sabry has long identified in the local ins. market. Most providers work with a limited network of large hospital groups, leaving a wide segment of smaller clinics and pharmacies outside the insured system — too administratively burdensome to onboard, too slow to pay. Fawry’s pitch is that it can change that by simplifying claims processing and shortening payment cycles. “We believe we will enable ins’ers to expand their offering to other market segments,” Sabry says.

Sehetak Fawry, the company’s earlier limited medical ins. product, was the proof of concept. It reached more than 700k beneficiaries by leveraging Fawry’s existing base — but it hit a ceiling, Sabry says. “The TPA will bring a more sophisticated offering to scale,” he adds, without elaborating on what specifically constrained the earlier product.

Where it gets consequential

Controlling utilization is central to the TPA’s value proposition. Medical ins. costs in Egypt are rising y-o-y, Sabry says, and without systems capable of managing clinical operations and controlling service costs, expanding coverage is economically unsustainable. “The healthcare system, once you create an ins. model, sees overuse, misuse, and abuse. The TPA is accountable for making sure spending is rational,” Islam Anan, professor of health economics and epidemiology at Misr International University, tells us.

In practice, that means Treemed TPA will have systems that flag — and in some cases block — certain prescriptions or procedures automatically, though Sabry is careful to draw a line. “Ins. policies, medications, and procedures all have rules that reflect both financial constraints and use of the right medication based on diagnosis, gender, and customer profile,” he tells us. “We use local and international databases to make sure there is no abuse, but the final decision is made by the doctor unless it clearly violates a clear rule.” His examples: adult medication cannot be prescribed to a child; a dose cannot exceed a treatment period; if two medications share an active ingredient, ins. policy determines which brand is covered.

The FRA source confirms that licensed TPAs have discretion to build fraud detection models and design medical approval protocols, provided they do not conflict with the terms of FRA-approved ins. policies and are not used to arbitrarily delay or withhold services from beneficiaries. The FRA views TPAs as active market participants — not neutral conduits — that negotiate with provider networks and generate data that ins. companies use to price medical products, the source says.

The conflict of interest question is harder to dismiss. Fawry is simultaneously building an ins. company, a TPA, and a payments platform — meaning it could be underwriting a policy, administering its claims, and processing its payments for the same patient. Sabry says this is a known tension Fawry has navigated before. “Since inception, Fawry clearly differentiates between being a platform serving the ecosystem and having its own clients. It is difficult and challenging, but we have done this successfully with many financial organisations that use our platform to facilitate business with their clients, while Fawry can have competing products directly offered to Fawry clients.” The analogy holds in fintech, but whether it holds in healthcare — where the stakes of a denied claim are categorically different from a declined payment — is a question the company has not yet had to answer at scale.

On data, Sabry says fraud detection is a standard TPA service offered to all ins. companies, including Fawry’s own microins. arm. He did not address whether patient data generated through Treemed TPA flows back into Fawry’s broader consumer and payments platform. This is the central unresolved question of the architecture, and it will matter more as the ecosystem grows.

What UHI does to all of this

The country’s universal health ins. rollout is the structural tailwind behind all of this. Anan argues UHI will not shrink the private ins. Market — it will expand it. Once basic state coverage exists, the private market will be selling supplementary products to a newly ins.-literate population. “It won’t just be 10% of the population covered by private schemes,” Anan says. “It could reach 40% of Egyptians subscribing to private ins. companies.” The FRA source describes the authority’s goal as moving the market from fragmented, ungoverned practice toward a system subject to periodic reporting, strict governance, and standardized medical codes and claims forms across the sector.

Anan is measured on whether that adds up to monopoly risk. “Technology alone does not create a monopoly. It depends on whether you have a strong health policy, whether the regulator is controlling and governing the system,” he says. “With a strong health policy, nobody can monopolize the system,” Anan adds.

What’s next: Sabry did not give specific targets for providers signed, lives covered, or market share over the next three years. For now, Treemed TPA is the licensed entity. What it becomes depends on how quickly Fawry builds out its network, whether ins. companies are willing to hand program administration to a fintech company with no prior healthcare operating history, and whether the platform vs. competitor distinction Sabry describes holds up once Fawry Healthcare is large enough that the difference matters.

This publication is proudly sponsored by

3

Tax

Office rents face VAT test

The government is moving to narrow the scope of its planned 14% VAT on leased administrative space, potentially keeping factories and buildings that provide direct services to citizens outside the tax net, three government officials tell EnterpriseAM. The change — which officials say follows IMF-backed recommendations to cut tax exemptions and raise revenues — could be written into the executive regulations to apply only to non-operational or non-service administrative premises.

A smaller pool, a softer pass-through. Limiting the tax to purely administrative premises would reduce how much of the burden falls on consumers while still bringing a broad class of office and administrative rents into the standard VAT regime. Officials are still studying the application mechanism, one official says.

The capital: Administrative buildings leased in the New Capital — including the government district — will be taxed, the officials say. The new budget puts government rents for New Capital buildings at around EGP 7 bn. Elsewhere in Greater Cairo, administrative towers, the Iconic Tower, and administrative zones in New Cairo, Sheikh Zayed, and other business districts are expected to fall under the tax, another official tells us.

A double-taxation question is still open. Some administrative units — particularly those inside malls and other customer-facing buildings — currently carry a 1% levy, one official says. Whether that survives alongside the new 14% VAT, or is scrapped to avoid double taxation, is still under discussion. New Cairo and New Administrative Capital Developers Association head Mohamed Albostany tells us the 1% charge had been enough as a tax cost on those premises.

REMEMBER- We reported earlier this month that the second tax facilitation package would bring leased administrative units under the standard VAT rate while allowing rent payments to remain deductible as business costs for income-tax purposes. The wider reform track is part of the Finance Ministry’s push to raise annual tax revenues by broadening the base rather than hiking headline rates.

A hit on paper, a hit on demand

Government sources tell us they do not expect the change to push companies to scale back their Egypt operations or investment plans, arguing that rent payments can be deducted from the corporate income-tax base as operating costs. That should cushion part of the hit, even if the VAT still changes the economics of leasing.

Developers are less hopeful. The new tax could curb investment demand for administrative units, which had been drawing buyers as company formation increased and demand shifted toward office premises, Albostany argues. Administrative units can generate rental yields of 8-10% — compared with 1-3% for residential units — but higher tax costs and softer demand could cool that activity, he adds. It could also weigh on companies that manage administrative buildings and towers — those that helped attract buyers to administrative units in recent years by managing or leasing the space on their behalf — but a higher tax burden on rents could make the model less appealing if passed through to tenants, he says.

Grade-A barely blinks

Landlords will try to preserve base rents and pass the VAT on to tenants, Ayman Sami, country head of JLL Egypt, tells us. Large Grade-A occupiers are unlikely to be materially hit by the standard VAT rate, but they will negotiate a middle ground that absorbs part of the increase into the existing lease economics, he explains. With many contracts already carrying automatic annual rent hikes of around 10%, the first year of application could see rents held flat before increases resume in later years, he adds.

Demand remains strong for administrative units, especially Grade-A space, Sami says. Spaces of 500-10k sqm are mostly suited to major corporates, developers, and large investors, while smaller investors tend to go for compact offices or clinics. A growing number of smaller investors are also pooling liquidity to buy larger administrative units in areas such as New Cairo to capture higher yields, he adds.

Companies stay, just with less space

The bigger competitiveness picture is still intact, Sami notes. Foreign companies weigh the total cost of setting up and operating, not rent alone, and Egypt still has a regional edge on operating costs and salaries, particularly when compared with other regional business hubs. The fact that USD-denominated office rents in Egypt have held up — or at least not fallen meaningfully — despite the float and broader economic pressure is a healthy sign for the market, he says.

The more likely adjustment is operational efficiency. Smaller footprints, more desk-sharing, and hybrid models that combine office and home work will likely be prioritized, rather than a shift away from offices altogether, Sami notes. Egypt has moved past the full remote-work phase that followed Covid-19, especially among foreign companies that follow policies set by global HQs, he notes.

WATCH THIS SPACE: The shape of the tax now sits in the executive regulations — whether the exemption holds for service and non-operational premises, and whether the 1% levy survives. Sami expects a period of uncertainty, delayed decisions, and price pressures before the market absorbs the cost. His broader ask is a cleaner tax architecture: a more unified system that improves competitiveness instead of layering property tax, VAT, and income tax on the same market.

Tags:

4

EGYPT IN THE NEWS

Rerouting sanctioned energy

Egypt’s role in the Russian oil products trade has caught the attention of the foreign press. Reuters reported that “nearly 140k tons of Russian fuel oil and vacuum gasoil loaded at Russian ports last month were destined for transfers near Port Said in Egypt, with the final destination ⁠unclear.”

BACKGROUND- Egypt’s Russian crude imports jumped 217% in April to 707k bbl / d from 223k bbl / d recorded in March. Meanwhile, product imports nearly doubled to 499k bbl / d, making up almost a quarter of Russia’s April seaborne product exports. Analysts told us in May that the surge reflected more than just Egypt’s need to replace disrupted supplies from the Gulf — it also showed the country positioning itself as a regional storage, blending, and redistribution hub for displaced cargoes. We were already one of the top destinations for Russian imports in 2024 and 2025.

5

Also on our Radar

Collectors on books

EgyServ and Egyptian International Firm are now the first companies registered to collect dues for NBFIs as the clock ticks down on the six-month grace period the Financial Regulatory Authority (FRA) gave firms in the sector to regularize their collection arrangements, according to a statement from the regulator. Once the grace period expires on 22 July, NBFIs will be barred from outsourcing collections to firms that are not on the new registry.

What changed: The FRA issued the registry framework and a six-month grace period in January under former FRA boss Mohamed Farid. The framework is now seeing its first registration under the new chief Islam Azzam, which requires collection firms to be registered with the authority, meet minimum capital and equity requirements (EGP 10 mn and EGP 20 mn respectively), get FRA approval for contracts with NBFI clients, and limit their work to collecting dues — not providing finance. The rules also tighten the money trail, barring collectors from routing recovered funds through their own accounts and requiring payments to move through approved noncash channels or checks issued to the creditor.

Ritz refresh, faster

Misr Hotels is cutting the Nile Ritz-Carlton Cairo’s renovation timeline to 12 months from 20, as high occupancy pushes the EGX-listed hotelier to accelerate the EGP 3 bn upgrade while keeping the property operating, the Arabic press reports, citing a company official. Misr Hotels tapped a US consultant to prepare room-upgrade samples for approval before work begins, with the overhaul targeting guest rooms, facilities, and services.

IN CONTEXT- The state’s 50.7% stake in Misr Hotels is currently in the process of beingtransferred to the Sovereign Fund of Egypt (SFE). We broke the news in February that the state is moving its most iconic hotels under the SFE to maximize asset value and reel in foreign capital.

6

PLANET FINANCE

A key Gulf export could be in trouble

The Gulf's USD 124 bn remittance machine is wobbling. The Iran conflict is stress-testing one of the world’s most consequential capital flows — the money sent home by roughly 30 mn foreign nationals working across the six GCC states. Bloomberg reports that GCC migrant workers sent an estimated USD 124 bn home in 2024 — and the early data from this year suggests the flow is under real strain for the first time since the pandemic.

We could be looking at a serious collapse in remittance volumes if foreign workers’ savings are depleted, potentially by 3Q 2026, due to a prolonged war, Daré Okoudjou, CEO of cross-border payments platform Onafriq, estimates. Around 40% of senders are already drawing from emergency reserves for the first time since the 2020 pandemic, Okoudjou adds.

The war’s opening weeks triggered a panic-send: Western Union reported an acceleration in outbound remittances from the Middle East during the early phase of the conflict, and the Central Bank of Kenya logged a surge as some 500k Gulf-based workers rushed money home at the onset. In India — where the UAE alone accounts for about one-fifth of all inward remittances — money sent home by overseas workers rose more than 28% in the three months through March. Bangladesh and Sri Lanka also reported increases.

Then came the hangover: Kenyan transfers from the Gulf states fell 18% in April. Philippine remittances grew at their slowest pace in almost four years — a warning sign for a country where inflows amount to about 10% of GDP and around 2.4 mn citizens work in the Middle East.

The savings buffer is the number to watch. Okoudjou says transaction volumes have risen, but the average transfer values have dropped about 12%, with wage delays — and in some cases cuts — pushing workers to draw from reserves.

It’s not just Okoudjou with the bearish outlook — Western Union CEO Devin McGranahan flagged the same bleak outlook on an earnings call in late April, explaining that prolonged conflict historically means less migration into the region, fewer economic prospects, and a gradual shrinkage of overall outbound volumes.

What to watch: How the US-Iran peace talks go over the next 60 days will play a huge role in remittance recovery, as the restoration of a sense of security and stability in the region will help its tourism, hospitality, and other industries begin a long road to recovery.

MARKETS THIS MORNING-

Asia-Pacific markets are down in early trading this morning, echoing a selloff seen on Wall Street on the back of expectations that the Fed may press ahead with aggressive monetary tightening later this year. South Korea’s Kospi is down 4.2%, while Japan’s Nikkei is down a more moderate 1.1%.

EGX30

52,586

-0.2% (YTD: +25.7%)

USD (CBE)

Buy 49.74

Sell 49.88

USD (CIB)

Buy 49.75

Sell 49.85

Interest rates (CBE)

19.00% deposit

20.00% lending

Tadawul

11,072

0.0% (YTD: +5.6%)

ADX

10,036

+0.2% (YTD: +0.4%)

DFM

6,183

+0.3% (YTD: +2.3%)

S&P 500

7,473

-0.4% (YTD: +9.2%)

FTSE 100

10,438

+0.7% (YTD: +5.1%)

Euro Stoxx 50

6,311

+0.3% (YTD: +8.9%)

Brent crude

USD 78.11

+0.3%

Natural gas (Nymex)

USD 3.23

-0.6%

Gold

USD 4,182

-0.3%

BTC

USD 64,340

+0.9% (YTD: +26.6%)

S&P Egypt Sovereign Bond Index

1,067

+0.2% (YTD: +7.4%)

S&P MENA Bond & Sukuk

152.21

-0.2% (YTD: +0.2%)

VIX (Volatility Index)

17.28

+3.0% (YTD: +15.6%)

THE CLOSING BELL-

The EGX30 fell 0.2% at yesterday’s close on turnover of EGP 9.3 bn (7.1% above the 90-day average). Local investors were the sole net sellers. The index is up 25.7% YTD.

In the green: GB Corp (+7.9%), Qalaa Holdings (+3.0%), and Telecom Egypt (+2.3%).

In the red: Abu Qir Fertilizers (-4.1%), Kima (-3.3%), and Emaar Misr (-2.9%).

7

Going Green

Six trades, 22 months

The Financial Regulatory Authority (FRA) gave non-banking financial institutions (NBFIs) six more months to comply with mandatory carbon reporting and offsetting rules — which industry sources say they are going to need. That isn’t because measuring emissions is complicated, though it is. It’s because the exchange from which they are required to buy credits — the Egyptian Climate Exchange (EGCX) — has logged six transactions totalling 6k credits since it launched in August 2024, prices its credits at 13-17x the global market rate, and can’t be accessed without hiring a licensed broker.

Why it matters: The FRA is about to layer mandatory demand from 80-200 NBFIs onto a market that has cleared, on average, one trade every three and a half months since launch. Whether that demand fixes the EGCX’s access and pricing problems or simply forces compliers into a market that doesn’t work is the question the December deadline will answer.

The mechanics: The extension covers the NBFIs required to measure, verify, and disclose Scope 1 and Scope 2 emissions. Resolution No. 115 of 2026, issued 4 June, pushes the compliance deadline to 31 December from the original 30 June cutoff. The underlying mandate — Decision No. 36 of 2026, issued in January under then-FRA chairman Mohamed Farid, now Investment and Foreign Trade Minister — requires companies with issued capital or net equity above EGP 100 mn to offset 20% of their reported emissions through the EGCX within 90 days of filing. The goal is to create forced demand on a currently inactive market.

A transaction record sparse enough to list in full. The EGCX transaction registry shows six trades since launch. The Minia Group project — an Egyptian domestic credit on the Economy of Love registry — traded three times — 500 credits at EGP 1k apiece in August 2024, and a further 500 credits across two November 2024 trades at EGP 1.3k per credit. The Wahat Group project, also on Economy of Love, traded once in May 2025 — 500 credits at EGP 1,000. The Punjab Agroforestry project, an Indian project on Verra, accounted for the remaining two trades — 2.5k and 1.5k credits on the same day in August 2024, both clearing at USD 18 per credit, within the global range for premium nature-based credits.

A black box dressed up as an exchange

Opacity is the first wall credit buyers and sellers hit on the EGCX. Unlike Verra or Gold Standard — where a corporate buyer registers online, browses projects by country, type, vintage, and retires credits the same day — the EGCX offers very little transparency: no public price feed, no live order book, no searchable project catalogue, Omar Ghaly, CEO and founder of the Egyptian Carbon Center, tells EnterpriseAM. “The EGCX does not offer this level of accessibility,” he says.

We found that a public project catalogue does exist on the EGCX platform, filterable by country, registry, sector, and methodology across all 27 registered projects, with each listing detailing the project developer, verification body, methodology, and available credit volume. Once a project clears international validation, a process that takes 12 to 18 months under Verra or Gold Standard, registration on the FRA's climate project registry takes around one month, Omar El Nemr, project management and structured finance head at VNV Advisory, tells EnterpriseAM, arguing that the framework is solid.

SOUND SMART- Verra and Gold Standard are the two largest voluntary carbon credit registries globally, certifying and tracking the bulk of internationally traded credits. Their public project catalogues and self-service retirement workflows are the operational benchmark against which any new exchange gets measured.

The EGCX system isn’t frictionless, either: “The platform requires you to go through a complex setup process mirroring traditional stock exchanges, where you must engage an investment bank or a licensed brokerage firm to buy or sell on your behalf,” Ghaly tells us. “This adds extra layers of bureaucracy, processing time, and additional brokerage fees. It acts as a massive barrier to entry.”

The result is a pricing picture that’s difficult to justify against global benchmarks. The four Egyptian domestic trades on the EGCX cleared at EGP 1-1.3K per credit — roughly USD 20 to USD 26 at current rates. The global going rate for renewable energy carbon credits, the most abundant category globally, runs between USD 1.50 and USD 2.00 per Ecosystem Marketplace data. With no competitive price discovery mechanism and no international buyers present to arbitrage the premium down, nothing is anchoring local prices to market reality.

Even buyers who clear the broker hurdle and reach the exchange face a more fundamental question: what does a carbon credit actually do for them? “Can I reduce my Scope 1 emissions? Does it count towards my Scope 2 emissions? Does it affect my CBAM compliance? Can I use it for SBTi ? Can I use it for the Greenhouse Gas Protocol ?” El Nemr asks — framing the questions that procurement and compliance teams across Egypt’s NBFIs are now beginning to ask.

The FRA itself appears to recognize the friction. Chairman Islam Azzam framed Resolution 115 as easing “the burden on the mandated companies” — institutional language that, five months into a year-old mandate, signals the regulator is aware compliance is harder than the original rule assumed. EnterpriseAM contacted a source at the FRA for comment on the issues discussed in this piece but received no response by deadline.

Was demand always going to be sparse?

The domestic demand base was thin long before the exchange had an access problem.

Fewer than 15 Egyptian companies are registered with net-zero targets under the Science Based Targets initiative, El Nemr tells us. Before Decision 36 of 2026, most corporate conversations about carbon credits ended the same way: purchasing is handled at headquarters. “Now we see procurement departments and compliance departments involved,” he says. “Now we have conversations with these companies regarding what a Scope 1 emission is, what Scope 2 emissions are, and what carbon credits are.”

“There is a general calm in the voluntary carbon market internationally,” El Nemr adds — pointing to unresolved uncertainty around Article 6 of the Paris Agreement and the aviation sector’s CORSIA mechanism as factors leaving corporates worldwide unsure about where credits fit in their decarbonization commitments. The answer, he argues, has to come from international standard-setting bodies before local markets can move. The SBTi's Corporate Net-Zero Standard Version 2.0, released June 11, is a potential inflection point — the first meaningful overhaul of the flagship corporate framework since 2021, and a signal, in El Nemr's view, toward greater clarity on how credits figure into net-zero target-setting. “Once you see clear signals and guidance on how to use carbon credits to reach climate targets, you will see an uptick not just globally, but also in Egypt,” he tells us.

Energy subsidy structures compound the problem at the industrial level. With heavily subsidized electricity tariffs, factory owners have no financial incentive to invest in solar infrastructure, generate credits, or buy them. The voluntary market is asking companies to spend money on something with no financial upside and — until Decision 36 of 2026 — no regulatory downside, Ghaly tells us. What would actually move the needle is phased industrial emissions mandates with real enforcement, and low-interest climate financing from the Central Bank to fund the transition. Local banks do not offer subsidized climate financing either, he adds — meaning companies that might want to invest in renewables or low-emission manufacturing have no affordable path to fund the transition in the first place.

The market that works bypasses the exchange

The credits that are actually moving are not doing so through the EGCX. Ghaly's Egyptian Carbon Center is the asset developer behind a large-scale jojoba agriculture project on the North Coast — roughly 21k acres, around 4 mn shrubs, and projected to generate some 3 mn carbon credits over a 30-year lifespan. The project has already secured advance interest from global corporate buyers for its initial credit vintages, flowing through international registries rather than the domestic exchange. “Global demand for high-quality, nature-based credits is robust,” Ghaly tells us, even as the EGCX sits quiet. This means the exchange's inaccessibility is not just a friction problem — it is actively routing the market’s best assets around it, at least on the evidence of the EGCX's first 22 months.

The FRA's regulatory architecture is more comprehensive than most comparable voluntary carbon markets. El Nemr — who develops carbon projects across 17 countries — says the framework covering project listing, validation, verification, and trade is the most rigorous he has encountered in any voluntary carbon market globally. “My fair assessment is we have not seen this level of inclusiveness and rigor that the FRA has introduced in any other markets we work in,” he tells us. That means the question the December deadline will answer is whether rules alone can build a market.

OUR TAKE- The FRA has created mandatory demand for a market that had none. Whether that is enough depends on three things going right at the same time: the exchange fixing its access problem before December, the FRA enforcing against firms that file the report and skip the offset purchase, and international standard-setting bodies delivering the clarity on credit use that El Nemr says the global market is waiting for.

What's next: Under Resolution No. 115 of 2026, reports are due 31 December 2026, with offset purchases required within 90 days — putting the first mandatory retirements on the EGCX in late 1Q 2027.


JUNE

23-25 June (Tuesday-Thursday): The Big 5 Construct Egypt, Egypt International Exhibition Center, Cairo.

23-25 June (Tuesday-Thursday): Watrex Expo, Egypt International Exhibition Center, Cairo.

30 June (Tuesday): June 30 Revolution.

JULY

9 July (Thursday): Monetary Policy Committee’s fourth meeting of 2026.

23 July (Thursday): Revolution Day (TBC).

AUGUST

19 August (Wednesday): Connected Banking Summit, Fairmont Nile City Hotel

20 August (Thursday): Monetary Policy Committee’s fifth meeting of 2026.

26 August (Wednesday): Prophet Muhammad’s birthday.

SEPTEMBER

8-10 September (Tuesday-Thursday) El Alamein International Airshow, El Alamein International Airport

10-12 September (Thursday-Saturday): Egyptian Entrepreneurship Sector Diagnostics Report Summit, El Gouna.

15 September (Tuesday): IMF to hold its eighth review of Egypt’s USD 8 bn EFF arrangement.

24 September (Thursday): Monetary Policy Committee’s sixth meeting of 2026.

27-29 September (Sunday-Tuesday): Global Conference on Population, Health, and Human Development.

OCTOBER

6 October (Tuesday): Armed Forces Day.

10-11 October (Saturday-Sunday): Egypt Women's Health Summit (EWHS), Cairo Marriott Hotel

26-28 October (Monday-Wednesday): IEX Egypt, Egypt International Exhibition Center, Cairo.

29 October (Thursday): Monetary Policy Committee’s seventh meeting of 2026.

DECEMBER

7-10 December (Monday-Thursday): Food Africa, Egypt International Exhibition Center, Cairo.

17 December (Thursday): Monetary Policy Committee’s eighth meeting of 2026.

EVENTS WITH NO SET DATE

1Q 2026: Trial operations for the Ain Sokhna-Sixth of October section of Egypt’s first high-speed rail line scheduled to begin.

May 2026: End of extension for developers on 15% interest rates for land installment payments.

July 2026: British Prime Minister Keir Starmer set to visit Egypt.

2H 2026: Operations at Deli Glass Co’s new USD 70 mn glassware factory kick off.

2026: The Egyptian-American Economic Forum.

4Q 2026: Banque du Caire IPO

2027

16-18 January (Saturday-Monday): Agri Expo, Cairo International Convention Center.

20 January-7 February: Egypt to host the African Games.

April 2027: Tenth of Ramadan dry port and logistics hub to begin operations.

EVENTS WITH NO SET DATE

2027: Egypt to host EBRD’s annual meetings.

2027: Egypt-EU Summit 2027.

End of 2027: Trial operations at the Dabaa nuclear power plant expected to take place.

September 2028: First unit of the Dabaa nuclear power plant begins operations.

Now Playing
Now Playing
00:00
00:00