EGX’s late-filing problem: Repeated fines, repeated extensions

1

WHAT WE’RE TRACKING TODAY

The CBE approved new rules allowing banks to verify customers entirely online

Good morning, folks. Egypt’s markets are growing, but not without some friction. We’ve got three stories about it today, covering the EGX, pharma, and real estate.

The EGX filing story is the most pointed read. About 50 companies were fined a combined EGP 1.04 mn last week for missing financial statements, the latest in a summer-long run of repeated penalties against the same names without results.

On pharma: Local insulin manufacturers are expanding capacity to meet export orders from Europe and Africa, but the Egyptian Drug Authority is keeping a close eye on domestic supply as producers scale up.

And in real estate: Al Ahly Sabbour, Beltone Mortgage, Property Finder, and Coldwell Banker Egypt are introducing the open-house model to Egypt. It’s a small format shift with a larger signal behind it: buyers are becoming more selective, and developers are having to compete on the product itself, not just the payment plan.

*** A QUICK NOTE FROM THE AUDIO TEAM- Morning Drive is taking a summer publication holiday today, Tuesday 25 August, and tomorrow Wednesday 26 August. We’ll be back in your feeds on Sunday 30 August. In the meantime, you can check out our other show Making It, an hour where the founders, CEOs, investors, and policymakers making the biggest decisions in our region show their work and talk about what’s next. You can find it on Apple Podcasts, Spotify, Anghami, and YouTube.

The EnterpriseAM Egypt Forum is back — and we’re devoting the full day to the singular set of questions on everyone’s mind: What does AI actually mean for your company, your people, your economy, your own job — and your kids’ future?

Every session on stage answers one question: “So, what do I actually do about it?”

Join us on 5 October in Cairo. Seats are limited and attendance is by invitation only.

Request your invitation here.


Verify once, bank anywhere

The Central Bank of Egypt’s (CBE) board has approved rules governing the eKYC identity system, which electronically identifies and verifies bank customers, letting banks verify customer identities digitally rather than in person, according to a CBE statement. Governor Hassan Abdalla said the system lets customers open accounts and access banking products entirely through digital channels — no branch visit required — with electronic acceptance of terms and conditions, e-authentication replacing wet signatures, and simplified data updates.

“The real shift in eKYC isn’t that the customer opens an account from their phone. It’s that their financial identity stops starting from zero every time they move from one bank to another,” banking expert Hany Abou El Fotouh tells EnterpriseAM. He says the rules allow a financial identity created electronically with a bank or other participating entity to be reused by another bank, subject to the customer’s electronic consent. “Converting paper procedures to electronic ones saves time. Reusing the digital identity goes further by preventing the same verification steps from being repeated at every bank,” he says.

That puts the spotlight on who runs the plumbing. The Digital Financial Identity Company (Haweya) manages and operates the system, including connecting participating banks to it, and the CBE holds a 55% stake. The system “isn’t an open space where institutions exchange customer data without restriction,” Abou El Fotouh says, adding that a digital identity’s value comes not only from ease of use but also “from trust in whoever manages it and whoever holds the right of access.”

Why it matters: A digital bank can’t function without a legal way to onboard customers who never set foot in a branch, and eKYC is that missing link. We flagged the groundwork back in February, including digital IDs, e-signatures, and strengthened AML frameworks that had lowered barriers to digital banking. CIB CEO Hisham Ezz Al Arab told us in April that the CBE had been introducing digital banking licenses, strengthening fintech regulation, and enabling tools such as eKYC and regulatory sandboxes to support financial-services innovation.

With the eKYC framework now adopted, banks must still clear licensing and operational-readiness steps for secure digital onboarding. Onebank has received final approval, while CIB’s Yomo has preliminary approval and is moving through technology validation, cybersecurity testing, and customer-journey work ahead of its targeted 4Q 2026 launch. The IMF says additional digital-bank applications remain under review and expects Egypt’s first fully licensed digital bank before the end of 2026, according to the Fund’s Seventh Review (pdf).

Switching gears for electric

The government is studying the launch of a 2027 scheme to replace conventional-fuel vehicles with locally assembled electric models. The proposed initiative would offer manufacturers cash incentives linked to sales, production volumes, and local value-added, with support potentially reaching 30% of a vehicle’s price, capped at EGP 150k. Companies would need to meet a minimum 45% local-content threshold, while offering competitively priced vehicles and aftersales services.

The program would not require motorists to surrender existing vehicles. Owners could either scrap their old cars for a scrappage payment or sell them and use the proceeds toward the down payment on a new EV. The initiative could cover private cars, taxis, and passenger vehicles, while the Industry Ministry also seeks to bring battery and charging equipment manufacturers into the scheme.

Why it matters: The proposal would add a consumer-demand component to Egypt’s wider EV-localization push, as the government separately weighs a 5% customs tariff on fully imported EVs to narrow the advantage enjoyed by imported models over local assemblers. It could also support planned local production, including SN Automotive’s reported upcoming launch of a locally assembled EV and Rox ESI Egypt’s luxury EV production, planned for mid-2027.

MEANWHILE- The localization pipeline is widening: Abou Ghaly Motors, Geely Global, and state-owned El Nasr Automotive signed an MoU to study locally assembling four Geely New Energy Vehicle (NEV) models in Egypt, Hapi Journal reports. Under the framework, El Nasr would provide manufacturing facilities and production-line modifications, Abou Ghaly Motors would invest in equipping the factory and lead marketing and exports, and Geely would provide technical support and localization guidance. The project remains at the feasibility study stage, with model selection, investment size, and a production timeline still to be determined.

Another delay?

The government is targeting the completion of the fair-value study for Misr Life Ins. by the end of September, a government official tells EnterpriseAM, a timeline that could push the state-owned insurer’s long-awaited EGX offering beyond earlier expectations. The study will determine the company’s valuation and must be approved by the Financial Regulatory Authority before the government sets the final timetable and structure of the offering, including the portion of shares to be sold, the official says. An independent financial adviser is preparing the study.

Why it matters: The new timeline is a further shift for an offering that had previously been penciled in for this year. Misr Ins. Holding Company approved a plan in June to float up to 20% of Misr Life on the EGX, with EFG Hermes acting as sole global coordinator and bookrunner. The insurer has held a temporary EGX listing since March.

The valuation process has already faced delays. The government expected to complete the fair-value study in late June, while a government official told us in July that it had been finalized — even as Investment Minister Mohamed Farid said that valuation details were still being finalized.

The potential sale is part of Egypt’s wider divestment program. The government is seeking a further USD 1.5 bn in asset-sale proceeds before its IMF program ends in December, after raising more than USD 500 mn by July, including from the Gabal El Zeit wind farm transaction.

Data point

USD 4.47 bn — that was how much Egypt’s food industry exported in the first seven months of 2026, a record for the period and up 10.7% from USD 4.04 bn a year earlier, according to a Food Export Council statement. The EU was the fastest-growing bloc (rising 18.6% to USD 1 bn), while Arab markets remained the single biggest destination at USD 2.06 bn, or 46% of total exports. Saudi Arabia, Spain, and Palestine led individual-market growth, and chocolate exports nearly doubled to USD 262 mn, making them the top contributor to the sector’s overall gain.


Destination Sahel Issue IV, the final issue in the series, drops this week, and we’re exploring how the North Coast could be more than a summer story.

Living in Sahel year-round is moving from a seasonal idea to a serious question; an industrial push is reshaping the Coast’s economic base, and Egyptian homebuyers are weighing Sahel against Dubai, London, and other Mediterranean markets for where to put their money.

In this issue, we get into what it would take for Sahel to work beyond the summer, how industry fits into the Coast’s next chapter, and the numbers behind the Sahel-vs-everywhere debate.

Coming straight to your inbox tomorrow.


PSA-

#1- The EGX (like us) is taking Thursday off. The bourse will be closed on 27 August for the Prophet’s birthday (Mawlid Al Nabi), according to a statement yesterday. Trading is set to resume on Sunday, 30 August.

#2- WEATHER- It’s hot and humid in Cairo today, with a high of 37°C and a low of 26°C, according to our favorite weather app.

It’s a little less intense in Alexandria, where temperatures will reach 33°C, with a low of 23°C.

The big story abroad

Washington has announced its latest attempt to squeeze Iran’s economy. Operation Economic Outcast includes sanctioning more than 60 entities, individuals, and vessels on a global level. Secondary sanctions may target entities doing business with Iran across several sectors, Treasury Secretary Scott Bessent said, warning Tehran’s trade partners to sever ties or face being expelled from the USD-based financial system.

Iran’s response? Tehran threatened military action and further cuts to Gulf oil exports before the US sanctions announcement, but Economy Minister Ali Madanizadeh later said the country was “fully prepared.” An IRGC spokesperson warned Iran would strike US vital interests and energy chokepoints if its infrastructure is threatened.

Washington’s ire toward Ottawa is also making waves, as US President Donald Trump threatened to raise tariffs on Canadian cars to 50% by 1 January and lock existing steel levies at the same rate. Last-minute trade talks collapsed over the weekend, triggering a new wave of US tariffs on USD 20 bn worth of Canadian goods and reigniting a trade war between the two nations.

A hedge fund under the microscope: The US Securities and Exchange Commission subpoenaed major Wall Street banks over trading activity at AI-focused hedge fund Situation Awareness. The fund narrowly avoided collapse after last month’s tech sell-off by selling the majority of its holdings to Citadel — a US hedge fund — in just 24 hours. The regulator will look into the timing of trades between Situation Awareness and its lenders, including Goldman Sachs, JPMorgan, Citigroup, and Bank of America.

*** It’s Going Green day — your weekly briefing of all things green in Egypt: EnterpriseAM’s green economy vertical focuses each Tuesday on the business of renewable energy and sustainable practices in Egypt, everything from solar and wind energy through to water, waste management, sustainable building practices and how you can make your business greener, whatever the sector.

In today’s issue: We look at why Chinese-backed assembly plants in Egypt still leave the country short of high-value ingot and wafer production, and buyers for their output.

Somabay Golf ranked among the world’s most spectacular golf-course settings

Somabay Golf is proud to be ranked #98 in Golf World’s Top 100 X Factor Courses, placing it among the world’s top golf courses and recognizing its extraordinary setting and unforgettable golfing experience.

Set between dramatic desert landscapes and the crystal-clear waters of the Red Sea, this recognition reflects the unique beauty, character, and world-class appeal that continue to position Somabay Golf on the global golf map.

**Click here to discover Somabay Golf.**

2

Capital markets

EGX keeps fining late filers as overdue financial statements pile up

The EGX’s listing committee fined roughly 50 companies a combined EGP 1.04 mn last week for missing financial statement deadlines. This marks the latest in a run of decisions this summer that have penalized the same names, session after session, without any of them producing their numbers, according to Youm7. Orascom Investment Holding and Qalaa for Financial Investments were each fined EGP 40k for failing to file both their 1Q and 2Q 2026 statements, as were Speed Medical, Arab Developers Holding, Ascom, and El Ahli Investment and Development.

Orascom Investment was late on its annuals, too: Shareholders only signed off on its FY 2025 financials on 17 August, about four and a half months after the 31 March deadline, according to a bourse filing (pdf). The same meeting set KPMG’s 2026 audit fee at EGP 2.1 mn, while the penalty for missing two quarterly filings is just EGP 40k — that is under 2% of what the company is paying to have the numbers produced in the first place.

The rules (pdf) give companies 45 days from the end of each quarter to submit their standalone and consolidated financial statements to the EGX and FRA, together with an auditor’s limited-review report. Annual financial statements must be approved by the ordinary general assembly within three months of year-end.

Miss either, and Article 64 of the executive procedures hands the listing committee a menu: It can grant up to 45 more days, impose a financial obligation, move the stock to a different trading list, or suspend trading in the security if the company doesn’t respond within the period it’s given. Late filers are also required to tell the market why they are late and when the numbers are coming. The committee has been reaching for the same item on that menu all summer. The fines run EGP 5k to EGP 40k, levied under the listing contract each company signs on its way in.

The fee isn’t what keeps companies on schedule: “The late filing fee is not, in itself, a material burden for large companies,” Kamel Saleh, managing partner and CEO of Saleh, Barsoum and Abdel Aziz — Grant Thornton, tells EnterpriseAM. The real discipline, in his telling, is reputational, or what the market does to a company that goes quiet, rather than what the exchange charges it. “The embarrassment of missing an announced or expected deadline, and the uncertainty it creates around the company’s financial results,” he says, adding that the uncertainty carries market consequences that outweigh the fee.

So, what does? Saleh traces on-time filing back to the listing process itself: roadshows, banker due diligence, and investor scrutiny tend to leave a company with reporting systems built to hit deadlines rather than scramble for them. “Somewhat counterintuitively, the more complex a company is, the more likely it is to have the right systems of internal control and controls over financial reporting to meet its deadlines,” he says. It’s the less complex, or simply less prepared, companies that fall behind.

Blue chips and large caps generally file on time; delays sit with small and mid caps, often alongside board disputes or unresolved director liability, Sameh Gharib, capital markets expert at Tycoon Securities, tells us. When a large company does slip a quarter or two, he says, it’s usually circumstantial, most often because the external auditor has raised points that send the company back to its balance sheet before it can file clean.

At the low end, the fee almost disappears: In a June session, the listing committee fined 18 companies EGP 5k apiece for missing 1Q 2026 standalone statements — among them state-linked industrial names including tobacco giant Eastern Tobacco and Egypt Alum, alongside South Valley Cement, National Drilling, and El Ahram Printing and Packing. The committee granted each of them a further 15 days in the same notice.

The company doesn’t blink

Digitize for Investment and Technology has been fined four times since early July, and the list of statements it owes keeps growing — EGP 10k, then EGP 20k for failing to convene its general assembly, then EGP 40k twice (here and here) for the statements themselves. That’s some EGP 110k in six weeks. The first of the EGP 40k penalties covered audited FY 2025 accounts and 1Q 2026. Two weeks later, 2Q 2026 had been added, and the committee fined the company and granted it another 15 days in the same breath. The FY 2025 accounts were due at a general assembly by 31 March.

The stock barely moved: Digitize’s shares have traded every session since, according to market data — at around 1.5 mn a day on average — while the market is still waiting on last year’s audited numbers. The latest fee came out yesterday, with the stock slipping 0.77% on the day to close at EGP 2.58.

This isn’t a case of Digitize falling between regulatory cracks: Article 64’s remedy for a company that misses its grace period is to bring it back before the committee, which fines it and grants a fresh grace period. There’s no automatic next step. The escalation the rule provides for moving the stock to a different trading list, or suspending it outright, is available but discretionary, and none of these decisions has gone further than a fine.

REFRESHER- Digitize, which offers a range of ICT solutions and engineering services, moved up from the EGX’s SME market in 2024 after growing its capital 8x since its debut in October 2023, Chairman Yousry Atlam said at the time. The SME market is a segment the exchange pitches as an incubator, where companies list for three to five years while they build toward a main-market listing. Graduating brings main-market filing obligations with it.

The fine hits the wrong party

“The EGP 40k fine is negligible,” Gharib tells us. The bigger problem is who pays it. The fine is levied on the company, not on the chairman or chief executive who missed the deadline, which means the cost comes out of shareholder returns. Take it to EGP 1 mn and that doesn’t change. There have been calls for years to move liability onto individuals, he says, but that would need legislative change that doesn’t exist. As things stand, a bigger fine only bites where executives hold meaningful equity in the company they run.

Personal liability would bite where it’s needed most: on the companies that stopped filing altogether. Not a quarter or two, but no approved results in years. Where a delay is genuinely outside management’s hands, Gharib says, an executive has nothing to fear from it. Where a company has chosen to sit on its numbers, the person who made that choice would be the one paying.

What’s next: 3Q statements fall due on the same 45-day clock in mid-November. The committee has more than fines available to it, with Article 64 letting it move a stock to a different trading list or suspend trading outright if a company doesn’t respond in the period it’s given.

(Tap or click the headline above to read this story with all of the links to our background as well as external sources.)

This publication is proudly sponsored by

3

PHARMA

Local insulin producers expand as export demand grows

Local insulin manufacturers are expanding capacity to meet new export orders from Europe and Africa, while seeking to preserve supply for the domestic market, sources at several producers tell EnterpriseAM. The companies are investing in additional production lines and higher output to fulfill the orders and access further export markets, the sources say.

“Egyptian-made insulin is currently exported to around 10 countries, including Cuba, Malaysia, and Kenya,” Ali Ouf, head of the Pharma Division at the Federation of Egyptian Chambers of Commerce, tells us. “There are requests from other countries to import the Egyptian product.”

BUT- The Egyptian Drug Authority is cautious about allowing exports that could affect domestic availability, Ouf says, making capacity expansion essential for companies seeking to serve both markets.

“There is no crisis or shortage of insulin in pharmacies,” Ouf argues, adding that the private sector, which accounts for around 80% of the country’s insulin market, has availability of roughly 95%. Egypt now has four insulin factories that have been operating for about a decade, he says, with local output meeting the needs of routine cases, which represent about 95% of insulin users. The state continues to secure supplies of newer and more specialized insulin types for the remaining 5%.

One producer tells us they currently supply more than 1 mn insulin packs to the domestic market each month, with most output sold locally and export volumes released only with Egyptian Drug Authority approval. Local manufacturers produce insulin in both vials and pens.

On quality: “Importing countries inspect Egyptian factories and request the necessary studies and quality certificates before allowing imports,” Ouf says, arguing that “the existence of these requests reflects the local industry’s ability to compete abroad after obtaining the required international accreditations.”

Building a local shield and a regional power: Egypt is looking to become a regional production and export hub for insulin, Ouf says. The local industry’s scale-up has also helped guard against supply disruptions, he adds, contrasting the 2018 insulin shortage — when Egypt was more dependent on imports — with a 2024 shortage, when domestic manufacturers increased production.

DATA POINT- Local insulin production could save the state around EGP 4 bn compared to imports, according to Ouf, who estimates that meeting the country’s insulin needs through imports would cost roughly EGP 8 bn, against around EGP 4 bn for locally made alternatives. For the whole country’s medical needs, he says local drugmakers now meet some 92% of needs, saving the country around USD 8 bn annually in import costs.

BACKGROUND- Eva Pharma began producing and selling locally manufactured insulin glargine with Eli Lilly in December 2024, saying then that it had signed MoUs covering exports to 56 countries and was targeting USD 100 mn in annual insulin exports by 2030. We also examined the wider push by local drugmakers into specialized manufacturing earlier this year.

More capacity is in the pipeline: Around 300 pharma factories are currently under construction in Egypt, Ouf says, as manufacturers expand into biotechnology, oncology meds, hormones, and active pharma ingredients. The Egyptian Drug Authority most recently put the number of licensed pharma factories at 183, saying domestic production covers 92-94% of demand for essential and chronic meds.

(** Tap or click the headline above to read this story with all of the links to our background as well as external sources.)

4

Real estate

Open-house model makes Egypt debut as buyers become more selective

Al Ahly Sabbour, Beltone Mortgage, Property Finder, and Coldwell Banker Egypt are teaming up to introduce the open-house property sales model to Egypt, bringing home viewing, property selection, and mortgage financing as part of the same package. The four companies are billing the initiative as the first of its kind in the Egyptian market.

What’s an open house? Common in more mature real estate markets, an open house allows prospective buyers to visit an actual home that is on the market, walk through the property, and experience what living there could look like before deciding whether to buy. The format differs from the sales offices and model units typically used to market residential projects in Egypt by putting the actual, completed property at the center of the sales experience.

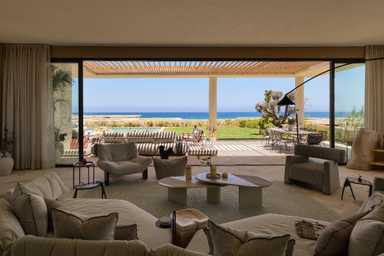
The first outing will take place on 27-29 August at Al Ahly Sabbour’s Amwaj development on the North Coast at a fully furnished, move-in-ready seafront home that is itself available for sale. Visitors will also be able to explore more than 1k ready-to-move units across Al Ahly Sabbour developments and speak directly with sales and mortgage advisers about available homes and financing options.

Who’s doing what: Al Ahly Sabbour brings the ready-to-move inventory, Beltone Mortgage provides mortgage financing options, Property Finder handles property discovery, and Coldwell Banker Egypt supports buyers in identifying and selecting properties. The idea is to reduce some of the friction between finding a home, evaluating it, figuring out how to finance it, and ultimately making a purchase.

Why it matters: The open-house model is another sign of how developers are having to work harder to stand out in an increasingly competitive market. Property is a big-ticket, long-term commitment, and buyers with more options are becoming increasingly selective about where they put their money. That is pushing the sales pitch beyond pricing and extended payment plans toward the product itself, the lifestyle around it, and the experience of buying it. Giving prospective buyers the chance to experience a finished home before committing, while having brokerage and financing options on hand, is one way of competing for that more discerning buyer.

(Tap or click the headline above to read this story with all of the links to our background as well as external sources.)

5

Also on our Radar

BHI is eyeing another fertility center in Egypt

B Healthcare Investments (BHI) is reportedly looking to buy another fertility center here. The specialized healthcare arm of EGX-listed private equity firm B Investments Holding has reached the final stages of acquiring one of the country’s largest fertility centers and expects to close within a month, Al Borsa reports, citing unnamed sources. Neither the size of the transaction nor the name of the target was disclosed.

REMEMBER- BHI bought a 51% stake in the Egyptian IVF Center — the first facility of its kind here — back in 2022. In August of last year, BHI was said to be closing in on two IVF and reproductive health hospitals, one in Egypt and one in Saudi Arabia, funded by a capital increase that brought CIB, Al Baraka Bank Egypt, Misr Ins., and Misr Life Ins. into the shareholder base. The Competition Authority cleared CIB for 25%, Al Baraka for 5%, and the two insurers for 20% later that month. B Investments sat out an EGP 387 mn tranche in January to make room for them, taking its own stake down to 25%, which means the firepower for an acquisition may already be in place.

With an eye on regional expansion: BHI is also studying stakes in — or outright buys of — hospitals and reproductive health centers in the UAE and Saudi, the sources said, with the stated aim of knitting the Egyptian and foreign assets into one regional platform. Ophthalmology and dentistry are also on the long list.

Heritage on show

Cairo Governorate is set to launch trial operations for the Restoring the Spirit of Cairo 30 program in the Magra El Oyoun area and in Old Cairo on Thursday, ahead of a formal opening the following week, a government official tells EnterpriseAM. The project aims to reposition the area as a tourism and cultural destination through regular heritage crafts and performing arts events. The initial phase includes a roughly 1k-sqm performance space and tour buses near the 57357 Hospital. The governorate plans to later lease space to artisans and vendors and host private events, aiming to increase tourism revenues and draw investment into the area.

BACKGROUND- The Magra El Oyoun redevelopment forms part of the wider Historic Cairo regeneration drive, which also includes the 500-feddan Fustat Park project and is intended to create private-sector prospects in the operation and management of restored heritage sites.

A month’s detention

The Financial Regulatory Authority (FRA) referred an unnamed consumer-finance company to the public prosecution and banned it from signing new financing contracts for one month over the Global Paradigm School loans scandal, the FRA said in a statement. The action follows allegations that the school used parents’ national ID data to arrange unauthorized loans, which the FRA previously said totaled EGP 319 mn across 619 clients and 839 contracts. The regulator said it has canceled all financial and credit obligations linked to affected parents. The measures are separate from the public prosecution’s parallel investigation.

(** Tap or click the headline above to read this story with all of the links to our background as well as external sources.)

6

PLANET FINANCE

The AI trade and the Fed are sitting the same exam this week

Markets get two verdicts this week, and they’re really the same verdict twice. AI chipmaker Nvidia is scheduled to release its financial results tomorrow in what’s already being read as a referendum on the AI trade itself. Then Kevin Warsh is set to deliver his first keynote as Fed Chair on Friday, which is officially about payments innovation, though nobody on a trading desk believes that’s where the real news sits, Bloomberg reports.

The rotation away from AI has persisted, even as some tech shares recovered. Bloomberg’s data show the 40-day correlation between a Goldman Sachs broad AI basket and the S&P 500 excluding AI swung to roughly -0.6, deeply negative for the first time. That points to money rotating out of AI: semiconductor and data-center names were deeply in the red over the past five trading days, while AI-victim, inflation-sensitive, and stagflation-sensitive baskets — including miners and energy — outperformed.

The AI thesis still has legs: AI-linked infrastructure companies are still responsible for about half of the index’s earnings growth, and Anthropic’s latest revenue topped USD 11.6 bn in 2Q against OpenAI’s roughly USD 6.7 bn. Meanwhile, Anthropic’s annualized revenue run rate topped USD 65 bn, compared with about USD 40 bn for OpenAI, according to Bloomberg. However, the market has stopped pricing AI as the only trade in town. There are now clear winners and laggards inside it, and that’s arguably driving as much of the rotation as any Fed signal.

Behind all of it sits the slower fuse: yields. US public debt hit a record USD 40 tn this week, and long bond yields are at 19-year highs, the FT reports, even after Treasury Secretary Scott Bessent committed to at least double long-end Treasury buybacks in the roughly USD 30 tn US government debt market, according to The Guardian. The 30-year yield had touched 5.30% before the Treasury’s buyback announcement pulled it back slightly, Bloomberg notes.

Warsh’s communication style is now part of the story. Warsh has signaled a distaste for forward guidance and said he wants to frame broader questions rather than focus narrowly on near-term policy. A survey of academic economists run for the FT by the University of Chicago’s Booth School suggests the experiment isn’t landing well: three-quarters call the pullback in Fed communication the single biggest shift since Warsh took over, and six in ten blame credibility worries for a meaningful share of this year’s climb in long yields. “The communication strategy is driving a loss of Fed credibility,” former Boston Fed president Eric Rosengren told the salmon-colored paper.

A reversal of the old playbook: What former Fed Chair and Nobel Economics Prize winner Ben Bernanke once named a “global savings glut” (cheap money chasing safe assets) has evolved into a global savings squeeze, Reuters reports, as rising government debt, fractured trade and supply chains, population aging, and AI investment compete for available capital. “Both the bond market and the FOMC have clearly decided to wake up,” Adam Posen of the Peterson Institute told Reuters, calling it the start of a multi-year uptrend in rates instead of a blip.

Positioning suggests traders don’t expect Warsh to keep this narrow either way. In the week marking mid-August, hedge funds bought US equities every day — Goldman’s prime desk called it the strongest three-week run since March 2020 — while global stocks were net sold at the fastest pace in two months last week, according to Goldman Sachs Prime Desk. Some 96% of the S&P 500 is in its corporate stock buyback window, with more than USD 1 tn in authorizations providing a steady bid; trend-following funds hold roughly USD 140 bn of global equities that could flip into USD 150 bn of selling in a sharp drawdown, with the first stop-loss triggers about 4% below current levels.

OUR TAKE- If Warsh wanted to prove the Fed doesn’t need to talk markets down anymore, this is a bad week to test that theory. Nvidia’s results are likely to remain a key test for the AI trade, while Warsh’s remarks could shape the market’s reading of rates and Fed policy. What Nvidia cannot resolve is the separate concern around long-term yields, where investors are weighing inflation, Treasury policy, government borrowing, and uncertainty about the Fed’s policy outlook.

(** Tap or click the headline above to read this story with all of the links to our background as well as external sources.)

MARKETS THIS MORNING-

Asian markets opened in the red earlier today, with South Korea’s Kospi down 2.3% and Japan’s Nikkei down 0.6%. Meanwhile, Wall Street equities are broadly trading at a loss as futures remain flat.

EGX30

55,165

-0.3% (YTD: +31.9%)

USD (CBE)

Buy 50.76

Sell 50.90

USD (CIB)

Buy 50.72

Sell 50.82

Interest rates (CBE)

19.00% deposit

20.00% lending

Tadawul

11,174

+0.9% (YTD: +6.5%)

ADX

10,048

+0.4% (YTD: +0.6%)

DFM

5.866

+0.2% (YTD: -3%)

S&P 500

7,653

-0.3% (YTD: +11.8%)

FTSE 100

10,854

+0.4% (YTD: +9.3%)

Euro Stoxx 50

6,448

-0.2% (YTD: +11.2%)

Brent crude

USD 92.17

-2.4%

Natural gas (Nymex)

USD 2.78

+0.3%

Gold

USD 4,698

+0.4%

BTC

USD 78,875

+1.7% (YTD: -10.0%)

S&P Egypt Sovereign Bond Index

1,102.41

+0.1% (YTD: +11.0%)

S&P MENA Bond & Sukuk

150.64

-0.2% (YTD: -0.8%)

VIX (Volatility Index)

15.86

+4.8% (YTD: +6.0%)

THE CLOSING BELL-

The EGX30 fell 0.3% at yesterday’s close on turnover of EGP 12.7 bn (16.9% above the 90-day average). Local investors were the sole net buyers. The index is up 31.9% YTD.

In the green: Misr Cement (+5.9%), Arabian Cement (+4.9%), and Egypt Aluminum (+3.9%).

In the red: Rameda (-4.4%), Heliopolis Housing (-3.5%), and Palm Hills Developments (-3.0%).

7

Going Green

Egypt’s solar factories are built, but demand is lagging

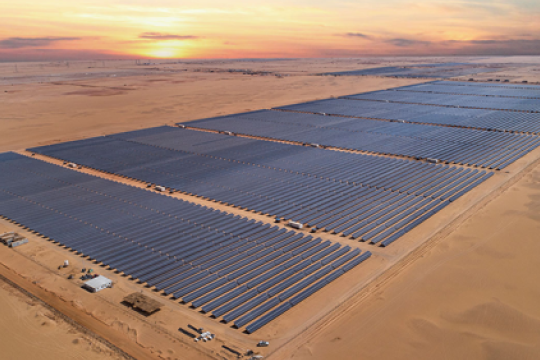
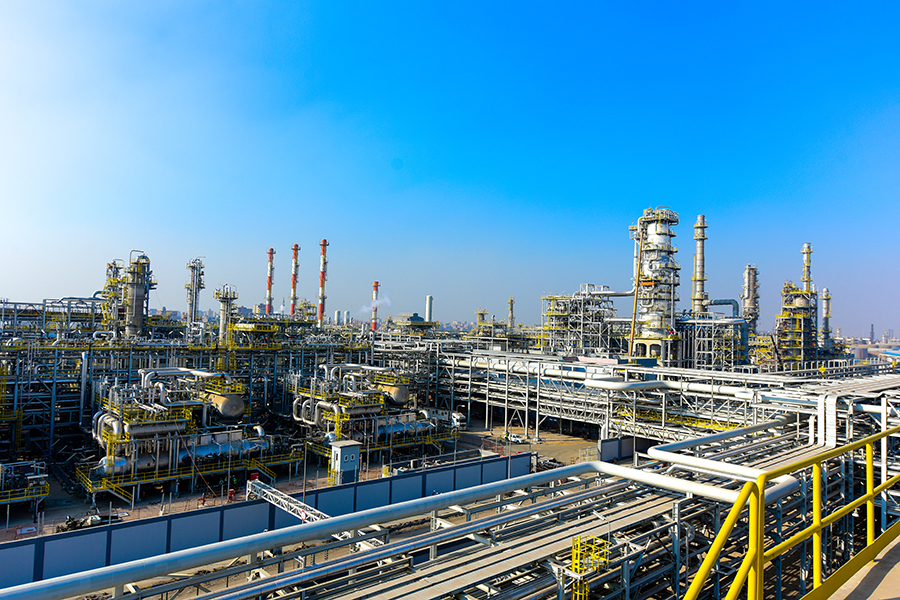
Egypt is trying to build its own solar components, but two things are lacking: the hardest stage of production, and buyers for what it already makes. A KfW Development Research paper warns that cheap Chinese solar locks developing economies into the low-value assembly stage, while the high-value stages, like building silicon ingots and wafers, stay in China. Five Chinese firms — EliTe, Sunrev, GCL, Cornex, and TBEA — have moved to build solar assembly plants in Egypt over the past 14 months, but Egypt is still facing key challenges.

Chinese solar panel imports into Africa hit a record 15 GW in the year to June 2025, up 60% y-o-y. Nigeria overtook Egypt as the continent’s second-largest importer of Chinese panels, behind South Africa, per Ember Energy.

Roughly 70% of solar project costs in Egypt remain USD-denominated because the highest-margin stage of production — turning raw quartz into silicon ingots and wafers — largely still happens outside the country. Egypt is sitting inside the exact bottleneck KfW warns about, further along than most countries on the Ember Energy list.

REMEMBER- We’ve tracked this wave for over a year. Three agreements account for the five firms above: EliTe Solar’s 5 GW facility, commissioned in January; Sunrev Solar’s USD 200 mn complex in Ain Sokhna; and GCL, Cornex, and TBEA’s USD 500 mn, 5 GW cell and module complex with local partner Kemet. Two more projects sit nearby but don’t belong in the same count: Kibing Group’s USD 685 mn solar glass factory in Sokhna makes panel glass, not cells, and a government-weighted USD 1 bn quartz-to-panel plant in Zafarana hasn’t been committed yet.

Not every megaproject here is about assembly. The Cabinet just gave a golden license to Nefer Minya, a plant co-developed by Infinity Power, the Masdar-Infinity Energy JV, and Hassan Allam Utilities, running on imported panels from China’s Aiko. EBRD and Meridiam are financing the project, not developing it.

Norway’s Scatec has signed a PPA for 1.95 GW of solar and 3.9 GWh of battery storage, for what the government calls “Energy Valley,” spread across Minya, Qena, and Alexandria. China’s Sungrow is supplying the batteries from a plant it’s building inside the SCZone, the first dedicated BESS factory in the Middle East and Africa.

The combined investment reaches USD 1.8 bn. “Localizing renewable energy industries is a fundamental pillar for strengthening energy security and the green transition,” PM Mostafa Madbouly said at the signing, calling the investment a sign of “global companies’ confidence in Egypt’s investment climate.” In January, Energy Valley drew preliminary financing from the European Investment Bank, the EBRD, and the African Development Bank, signed alongside Scatec’s Mohamed Amer.

The Sungrow battery storage plant broke ground on 17 August in the TEDA zone at Ain Sokhna, a USD 50 mn, 100+ job investment. SCZone Chairman Mostafa Sheikhoun called it proof of the zone’s “developed infrastructure and integration between industrial zones and ports.” Industry Minister Khaled Hashem went further, calling it “a new chapter” in Egypt-China industrial ties.

A government official tells EnterpriseAM that local manufacturing is “a fundamental pillar” of the energy strategy, tied to a 42% renewables target and 80 GW of planned generation capacity. Egypt wants to raise local content in solar panel manufacturing from 60% today to 80% by 2030. That’s a real, numbered commitment, but it doesn’t say who’s buying the output in the meantime.

Ayman Haiba, executive director of the Sustainable Energy Development Association, tells EnterpriseAM that localization won’t succeed without a large domestic market for clean energy. That means updated regulations and low-interest financing around 5%, funded by gas-import savings rather than the state budget. “We understand this direction, but what we’re asking for is support for accessible financing and green loans,” he says, flagging that the government has frozen further customs and tax exemptions beyond what’s already in place.

One number, from Cairo Solar Managing Director Hatem Tawfik, captures the demand side of the gap. Total solar panel import value into Egypt runs around USD 150 mn, small next to what these new factories can produce. “The market is still very small compared to the capabilities of these factories, which limits movement on the localization file,” Tawfik says. His own read on where the output goes: exports first, local demand second, at least for now.

And on the supply side, the gap has no fixed date either. Sunrev’s own Phase II, the USD 110 mn stage meant to bring ingot and wafer production to Egypt, has carried no date since it was announced in mid-2025. No one, not the company, not the government, has said when that will change.

Ingot and wafer production is the most China-concentrated stage of the entire solar supply chain, and that’s true well beyond Egypt. Even the US, backed by IRA subsidies, draws skepticism over whether its own announced plants land on schedule, per pv magazine USA.

Egypt’s white sand reserves, the raw quartz feedstock for silicon production, are the one upstream input the country already controls. The Investment and Foreign Trade Ministry banned white sand ore exports in 2025, keeping the raw material in the country. It doesn’t solve the actual bottleneck: turning that raw material into ingots and wafers.

What to watch: Whether the 60-80% local-content target becomes an actual decree, or stays a talking point. Whether ingots and wafers are included, or quietly excluded. Whether Sunrev’s Phase II gets a date. And whether Haiba’s push for cheap financing and grid access for renewables goes anywhere, since that’s the only thing that actually builds a market for what these factories make.

OUR TAKE- Egypt hasn’t escaped the trap the KfW warns about. Instead, it’s caught in it twice over: assembly instead of the full value chain, and factories instead of buyers. The local-content target, the white sand ban, the incentive stack — all of those are policies, but whether any of it becomes an industry depends on two things nobody has fixed yet: who buys the output, and who brings the ingots and wafers home.

(** Tap or click the headline above to read this story with all of the links to our background as well as external sources.)


AUGUST

26 August (Wednesday): Prophet Muhammad’s birthday.

31 August (Monday): Deadline to apply online for the Industrial Development Authority’s 540 lease-to-own industrial plots via the Egypt Industrial Hub

SEPTEMBER

8-10 September (Tuesday-Thursday) El Alamein International Airshow, El Alamein International Airport.

10-12 September (Thursday-Saturday): Egyptian Entrepreneurship Sector Diagnostics Report Summit, El Gouna.

15 September (Tuesday): IMF to hold its eighth review of Egypt’s USD 8 bn EFF arrangement.

24 September (Thursday): Monetary Policy Committee’s sixth meeting of 2026.

27-29 September (Sunday-Tuesday): Global Conference on Population, Health, and Human Development.

28-29 September (Monday-Tuesday): Egypt Mining Forum, St. Regis Hotel New Capital.

30 September - October 3 (Wednesday-Saturday): Cityscape, Egypt International Exhibition Center, Cairo.

OCTOBER

5 October (Monday): The EnterpriseAM Egypt Forum.

6 October (Tuesday): Armed Forces Day.

10-11 October (Saturday-Sunday): Egypt Women’s Health Summit (EWHS), Cairo Marriott Hotel.

26-28 October (Monday-Wednesday): IEX Egypt, Egypt International Exhibition Center, Cairo.

29 October (Thursday): Monetary Policy Committee’s seventh meeting of 2026.

NOVEMBER

6-8 November (Friday-Sunday) : Global Entrepreneurship Festival, JW Marriott Hotel, New Cairo.

8-11 November (Sunday-Wednesday): Cairo ICT Forum.

DECEMBER

7-10 December (Monday-Thursday): Food Africa, Egypt International Exhibition Center, Cairo.

17 December (Thursday): Monetary Policy Committee’s eighth meeting of 2026.

EVENTS WITH NO SET DATE

2H 2026: Operations at Deli Glass Co’s new USD 70 mn glassware factory kick off.

2026: The Egyptian-American Economic Forum.

4Q 2026: Banque du Caire IPO.

2027

20 January-7 February: Egypt to host the African Games.

1-3 February (Monday-Wednesday): Agri Expo, Cairo International Convention Center.

April 2027: Tenth of Ramadan dry port and logistics hub to begin operations.

EVENTS WITH NO SET DATE

2027: Egypt to host EBRD’s annual meetings.

2027: Egypt-EU Summit 2027.

End of 2027: Trial operations at the Dabaa nuclear power plant expected to take place.

September 2028: First unit of the Dabaa nuclear power plant begins operations.

Now Playing
Now Playing
00:00
00:00